Diwali stock picks! Axis picks Eternal, Hindalco, 7 other stocks with upside potential of up to 20%. See full list
1/10
Diwali Picks
Samvat 2082 proved challenging for Indian equities, marked by heightened volatility, intermittent recoveries and a significant correction in benchmark indices. Over the next 12 months, the sustainability and breadth of corporate earnings growth are likely to be the key drivers of equity market returns. Here are 9 stocks Axis Direct is bullish on this Diwali.
2/10
Eternal
The food delivery major has a target of Rs 365, an upside of 15% from current levels. Axis says higher discounting to drive customer acquisition and order frequency is delivering positive outcomes in user growth and engagement. EBITDA margins are likely to remain broadly flat over the next 1–2 years as the company prioritises market expansion.
3/10
DCB Bank
With a target price of Rs 240, the brokerage forecasts 20% upside from current levels. Axis says the lender is set to enter H2 with strong business momentum, improved visibility on NIM improvement, healthy asset-quality indicators and a demonstrated ability to generate operating leverage, collectively contributing to a sustainable 1-1.05% RoA delivery.
4/10
Nephrocare Health Services
With a target price of Rs 710, Axis sees 20% upside potential. Nephrocare is well-positioned to benefit from growing demand for dialysis, increasing outsourcing by hospitals and the expansion of organised healthcare in India. Its international presence, recurring treatment demand and improving operating margins provide a strong growth platform.
5/10
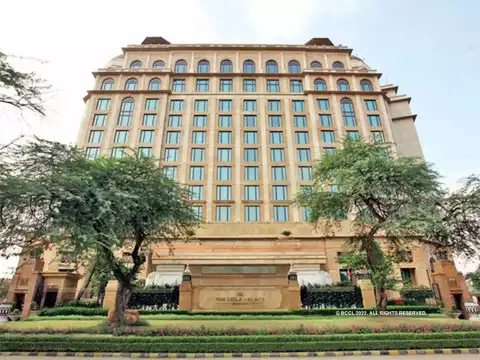
Indian Hotels Company
Axis has pegged the target price at Rs 900, an upside of 15%. While Taj-SATS is expected to experience a muted year due to geopolitical disruptions affecting air travel, IHCL is well-positioned to deliver healthy growth, supported by strong occupancy trends across key tier-1 cities, improving contributions from newly opened hotels, and its focused diversification into select-service segments.
6/10
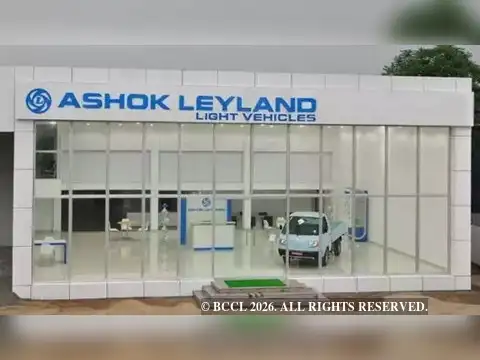
Ashok Leyland
Axis analysts have pegged the target at Rs 170, upside of 17% from here on. Analysts remain constructive on long-term prospects, supported by MHCV replacement demand, higher-horsepower products, LCV share gains and exports, Defence, EVs and financial services. However, commodity inflation remains a near-term risk.
7/10
Coforge
With a target of Rs 2,245, Axis analysts forecast 18% upside from current levels. From FY20-26, Coforge has delivered a Revenue/EBIT/PAT CAGR of 26%/26%/24%, led by healthy momentum in deal wins and client additions across key verticals, particularly BFS and travel, transportation and hospitality.
8/10
Hindalco
With a share price target of Rs 1,000, analysts see 15% upside potential. While LME aluminium prices have corrected amid easing supply concerns in the Middle East and higher aluminium production from China and Indonesia, Hindalco is expected to deliver stable performance, largely supported by Novelis.
9/10
APL Apollo Tubes
Axis analysts have pegged the target at Rs 2,340, an upside of 15% from current levels. Management has highlighted war-driven global disruptions and near-term sector headwinds, such as steel price increases, channel destocking, and energy/labour shortages. As a result, the earlier FY27 volume growth guidance of 20% YoY was revised to the lower end of 15-20%.
10/10
Elecon Engineering
With a target of Rs 500, Axis forecasts 20% upside potential in the stock. Elecon is well-positioned to capitalise on sustained domestic investments in steel, power and cement, alongside improving overseas enquiries and recovery in global markets. Supported by its leadership in Gear and MHE, advanced manufacturing capabilities, and customised engineering solutions, the company expects 15% revenue growth in H2FY27.
Disclaimer: This article has been written by Veer Sharma, who is not a SEBI-registered Research Analyst or an Investment Adviser. Veer Sharma and his/her ‘relative(s)’ (as defined under Section 2(77) of the Companies Act, 2013) do not hold any financial interest in the companies mentioned in this article as of the date of publication. The views/recommendations mentioned in this article, wherever applicable, are those of the respective SEBI-registered Research Analyst/brokerage and have been reproduced/reported with due attribution. They should not be construed as the views or recommendations of The Economic Times Digital or the journalist. Readers are advised to consider the original research report and make their investment decisions based on their own assessment. Brokerage disclaimers here .
Disclaimer: This article has been written by Veer Sharma, who is not a SEBI-registered Research Analyst or an Investment Adviser. Veer Sharma and his/her ‘relative(s)’ (as defined under Section 2(77) of the Companies Act, 2013) do not hold any financial interest in the companies mentioned in this article as of the date of publication. The views/recommendations mentioned in this article, wherever applicable, are those of the respective SEBI-registered Research Analyst/brokerage and have been reproduced/reported with due attribution. They should not be construed as the views or recommendations of The Economic Times Digital or the journalist. Readers are advised to consider the original research report and make their investment decisions based on their own assessment. Brokerage disclaimers here .