₹10 lakh investment in gold: Know how physical gold, ETFs & SGBs differ on returns, risk and tax
1/7
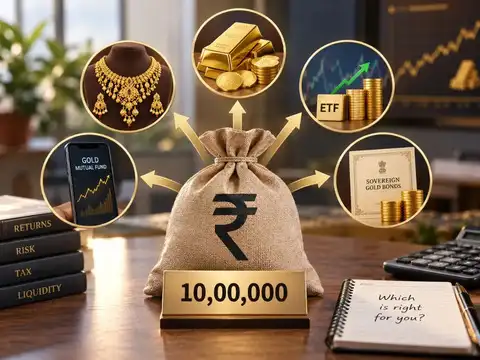
₹10 lakh in gold: Where should you invest it?
Gold can be bought in several forms, but the investment experience can be very different.
If you have ₹10 lakh to invest in gold, should you buy jewellery, physical bars and coins, Gold ETFs, gold mutual funds or SGBs?
The right choice depends on what you want from gold: price exposure, liquidity, income, safety or long-term holding.
If you have ₹10 lakh to invest in gold, should you buy jewellery, physical bars and coins, Gold ETFs, gold mutual funds or SGBs?
The right choice depends on what you want from gold: price exposure, liquidity, income, safety or long-term holding.
2/7
Physical gold: Tangible, but comes with costs
Buying gold bars or coins gives you direct ownership of the metal.
Advantages
You physically own the gold
No demat account required
Can be gifted or passed on to family
Useful if physical possession is important
Watch-outs
Making charges/premiums can increase the purchase cost
Storage and security become your responsibility
Selling price may differ from the market price
Jewellery is generally less efficient as a pure investment because of making charges
For ₹10 lakh: A large allocation to physical gold means you also need to think about storage and resale.
Advantages
You physically own the gold
No demat account required
Can be gifted or passed on to family
Useful if physical possession is important
Watch-outs
Making charges/premiums can increase the purchase cost
Storage and security become your responsibility
Selling price may differ from the market price
Jewellery is generally less efficient as a pure investment because of making charges
For ₹10 lakh: A large allocation to physical gold means you also need to think about storage and resale.
3/7
Gold ETF: Gold exposure without storing gold
Gold ETFs are designed to track domestic gold prices and trade on the stock exchange.
Why investors consider them
No physical storage required
Can be bought and sold through a demat account
Transparent market-linked pricing
Convenient for portfolio allocation
Costs to consider
Expense ratio
Brokerage and other transaction costs
Demat-related charges, depending on the investor
For someone primarily seeking gold-price exposure rather than physical possession, an ETF can be a convenient route.
Why investors consider them
No physical storage required
Can be bought and sold through a demat account
Transparent market-linked pricing
Convenient for portfolio allocation
Costs to consider
Expense ratio
Brokerage and other transaction costs
Demat-related charges, depending on the investor
For someone primarily seeking gold-price exposure rather than physical possession, an ETF can be a convenient route.
Amazon Top Deals
POWERED BY
4/7
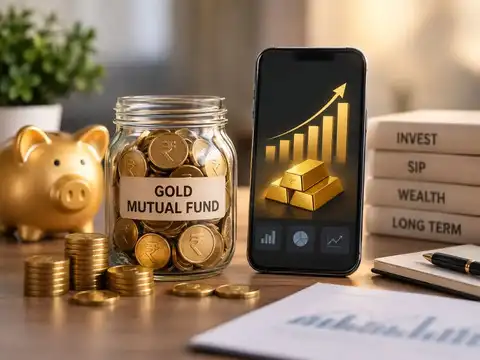
Gold mutual funds: Simpler route for some investors
Gold mutual funds, including fund-of-fund structures that invest in Gold ETFs, offer another way to gain exposure to gold.
Potential benefits
No need to store physical gold
Can be bought through a mutual fund platform
SIP facility may be available
Useful for investors who already use mutual funds
But remember:
The fund's expenses and structure can affect returns, so investors should check the expense ratio, underlying ETF and taxation before investing.
Potential benefits
No need to store physical gold
Can be bought through a mutual fund platform
SIP facility may be available
Useful for investors who already use mutual funds
But remember:
The fund's expenses and structure can affect returns, so investors should check the expense ratio, underlying ETF and taxation before investing.
5/7
SGBs: The unique gold investment
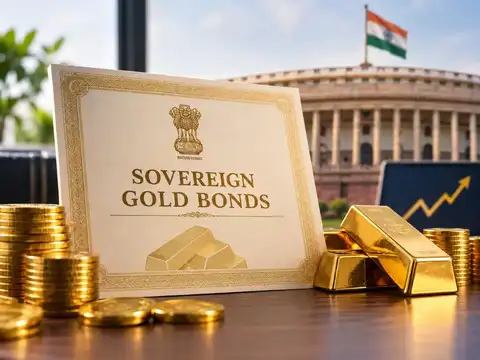
Sovereign Gold Bonds were designed to provide gold-price exposure through a government security.
Historically, SGBs offered:
Gold-linked returns
2.5% annual interest, paid semi-annually
No need to physically store gold
A maturity period of eight years, with specified early-redemption opportunities
However, fresh SGB issuance and current availability should be checked before investing, because investors cannot simply buy a new issue whenever they want.
For existing SGBs, the purchase price, remaining maturity, liquidity and tax treatment all matter.
Historically, SGBs offered:
Gold-linked returns
2.5% annual interest, paid semi-annually
No need to physically store gold
A maturity period of eight years, with specified early-redemption opportunities
However, fresh SGB issuance and current availability should be checked before investing, because investors cannot simply buy a new issue whenever they want.
For existing SGBs, the purchase price, remaining maturity, liquidity and tax treatment all matter.
6/7
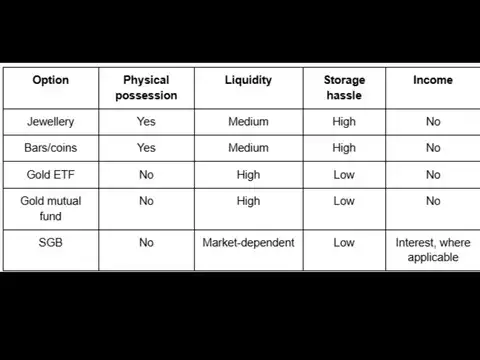
₹10 lakh: Don't put it all in one form of gold
A ₹10 lakh gold allocation can therefore look very different depending on whether the priority is convenience, physical ownership, liquidity or long-term holding.
7/7
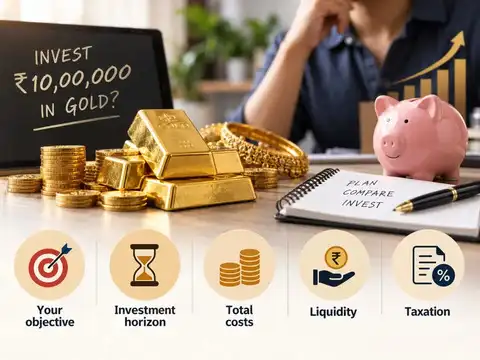
Before investing ₹10 lakh in gold, check these 5 things
1. Your objective
Are you seeking diversification, wealth preservation or physical gold?
2. Investment horizon
Gold can behave differently over short and long periods.
3. Total costs
Compare premiums, making charges, expense ratios and transaction costs.
4. Liquidity
Check how easily and at what price you can exit.
5. Taxation
The tax treatment varies by product and by the date and manner of purchase. Check the applicable rules before investing.
Bottom line:
There is no single gold product that suits every ₹10 lakh investment. The decision should depend on why you are buying gold, how long you plan to hold it and whether you need physical possession.
Are you seeking diversification, wealth preservation or physical gold?
2. Investment horizon
Gold can behave differently over short and long periods.
3. Total costs
Compare premiums, making charges, expense ratios and transaction costs.
4. Liquidity
Check how easily and at what price you can exit.
5. Taxation
The tax treatment varies by product and by the date and manner of purchase. Check the applicable rules before investing.
Bottom line:
There is no single gold product that suits every ₹10 lakh investment. The decision should depend on why you are buying gold, how long you plan to hold it and whether you need physical possession.