What happens to your corporate NPS after a job change? A 2026-27 guide
1/9
Changed jobs? Your corporate NPS stays yours
Switching companies does not mean losing your retirement savings. Your Corporate National Pension System (NPS) account remains active and belongs to you, whoever your employer is. You don’t need to withdraw your money or open a new account. Swipe to see exactly what happens to your NPS corpus, what to tell your new employer, and the simple steps that keep your pension on track.
2/9
Your money keeps growing, without a break
Your accumulated NPS savings stay invested after you leave your job. They continue to grow and compound without interruption. A job change and your investment performance are two separate matters. Your corpus is linked to your account, not to your employer, so moving to a new company does not reduce, reset or close it.
3/9
Your PRAN is yours for life
Your 12-digit Permanent Retirement Account Number (PRAN) is your unique NPS identifier. It is not an employee number issued by a company. It stays with you for life, across employers and locations. PFRDA’s framework is built to make NPS portable, so you should never need a new PRAN just because you changed jobs. Keep your PRAN and account details handy before joining your next organisation.
4/9
New employer offers NPS? Share your existing PRAN
Tell your new HR or NPS team that you already have an NPS account, and give them your existing PRAN and personal details. They will link (tag) it to their corporate setup so employer and employee contributions can resume. Don’t let them generate a new PRAN. How contributions work depends on the new company’s Corporate NPS structure, so ask HR about it early.
5/9
No NPS at your new job? Switch to the all citizen model
If your new employer doesn’t offer Corporate NPS, you can still continue. Move your account to the All Citizen Model (Individual NPS) through Inter Sector Shifting (ISS) on the Protean CRA portal, or through a registered Point of Presence (PoP). After that, you can make voluntary contributions on your own. Your account does not become a different kind of account just because you changed jobs.
6/9
Don’t close it. Don’t withdraw it
The most important rule when switching jobs is to leave your existing NPS account alone. Closing it or withdrawing from it is unnecessary, and it breaks the continuity of your retirement savings. Your account stays tied to your PRAN, and your future contributions depend only on the arrangement with your new employer or the route you choose to continue.
7/9
Update your details before you move on
Keep your NPS account information current when you switch jobs. Check your registered mobile number, email address, bank account and nominee details. Outdated details can cause problems with communication, transactions and claims later. A few minutes of updating now protects your savings and your family’s interests for years.
8/9
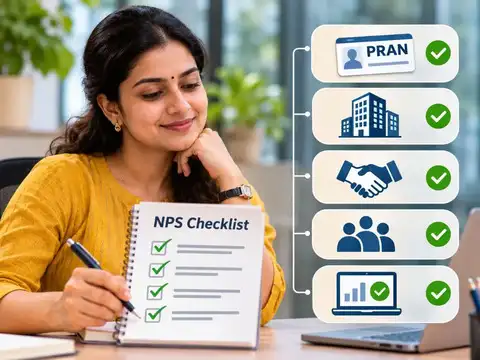
Your job-switch NPS checklist
*Keep your PRAN and NPS account details ready before you join.
*Check whether your new employer offers Corporate NPS.
*If the answer is yes, share your existing PRAN and complete the required process.
*If the answer is no, explore continuing under the All Citizen Model through a registered PoP.
*Review your account afterwards to confirm the employer association and transactions show correctly.
*Check whether your new employer offers Corporate NPS.
*If the answer is yes, share your existing PRAN and complete the required process.
*If the answer is no, explore continuing under the All Citizen Model through a registered PoP.
*Review your account afterwards to confirm the employer association and transactions show correctly.
9/9
Your NPS moves with your career
Changing jobs doesn’t mean starting your NPS journey over. Your PRAN is portable, your corpus stays invested, and you can continue with a new employer or on your own. Log in to the Protean CRA portal to review your account and take the next step in managing your retirement savings.