Stop your SIP too early or start your SWP too soon? Here’s how to get the timing right
1/10
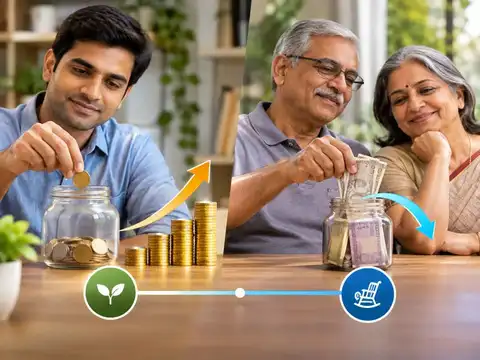
Your money has two lives. Are you ready for both?
Every investor goes through two phases. First, you build wealth with a Systematic Investment Plan (SIP). Later, you turn that wealth into income with a Systematic Withdrawal Plan (SWP). Which one you need depends on your age, your goals, and where you stand on your financial journey. Get the balance right, and your money keeps compounding without running out too soon.
2/10
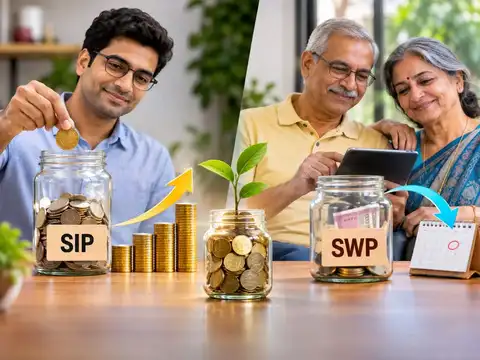
SIP builds wealth. SWP pays the bills
Think of SIP as the engine of your earning years. You invest a fixed amount regularly and let compounding do the heavy lifting. SWP is the tool for the next stage. It lets you draw a steady income from your investments when your salary stops or a big goal arrives. One builds the pot. The other pays you from it.
3/10
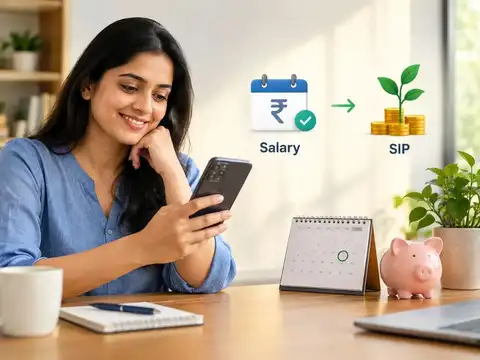
Pay yourself first: Match your SIP date to payday
The easiest way to stay disciplined is to set your SIP date right after your salary lands. The money is invested before you have a chance to spend it. No willpower needed, no “I’ll invest next month” excuses. Automating your investing on payday turns saving into a habit you never have to think about.
4/10
The step-up trick that shortens your wealth journey
Raise your SIP by a fixed percentage, such as 10%, every year when your salary goes up. You will barely feel the change, but your corpus grows much faster. A step-up SIP can cut the years needed to reach your goal because each year’s investment builds on the last. Small yearly increases make a big difference over time.
5/10
Never pause your SIP in a market crash
When markets fall, many investors panic and stop their SIPs. That is often the costliest mistake. A falling market means your fixed amount buys more units at lower prices, which is the idea behind rupee-cost averaging. When markets recover, those extra units work harder for you. Stay invested through the dips.
6/10
When should an SWP start?
Start an SWP only when you need regular cash flow from your investments. The most common trigger is retirement, when systematic withdrawals replace your monthly salary. It can also fit a specific goal, such as paying for a child’s four-year higher education. If you don’t need the income yet, let your money keep growing.
7/10
The 3-year safety buffer every retiree needs
Here is a hidden danger: if the market crashes just as your withdrawals begin, you sell units at low prices and lose capital for good. This is called sequence of returns risk. To protect yourself, move part of your equity into conservative debt or liquid funds at least three years before starting your SWP. That cushion helps you ride out early storms.
8/10
SIP vs SWP at a glance
Goal: SIP builds wealth. SWP generates income.
Market volatility: SIP benefits from it, buying more units when prices are low. SWP is hurt by it, since selling in a crash permanently erodes capital.
Best funds: SIP suits equity funds for long-term growth. SWP suits hybrid, arbitrage, or debt funds that preserve capital.
Amount: SIP depends on your surplus savings. SWP should stay at roughly 4% to 6% of your corpus per year
Market volatility: SIP benefits from it, buying more units when prices are low. SWP is hurt by it, since selling in a crash permanently erodes capital.
Best funds: SIP suits equity funds for long-term growth. SWP suits hybrid, arbitrage, or debt funds that preserve capital.
Amount: SIP depends on your surplus savings. SWP should stay at roughly 4% to 6% of your corpus per year
9/10
The 4%–6% rule: Don’t withdraw more than your money earns
An SWP runs out of money when you withdraw faster than your portfolio grows. If your investments return around 8% a year, keep withdrawals below 6%. That leaves room to beat inflation and protect your original corpus. A withdrawal rate of 4% to 6% of your total corpus is the sustainable zone for most retirees.
10/10
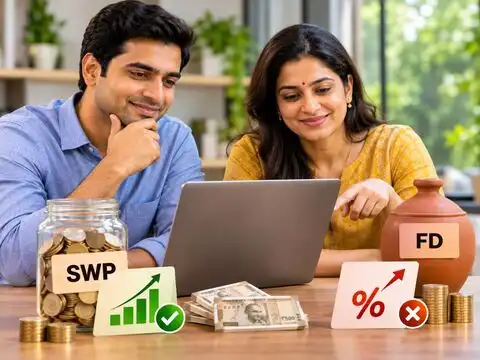
Why SWP can beat a fixed deposit on tax
In many tax systems, SWP withdrawals are treated as capital gains, so only the profit portion is taxed, not the whole payout. A fixed deposit’s interest, by contrast, is usually taxed as regular income. This can leave you with more money in hand. Tax rules vary by country and change over time, so check the current rules or talk to a qualified advisor before you decide.
This is general information, not personalised financial advice. Returns and tax treatment vary, so consult a SEBI-registered advisor for your situation.
This is general information, not personalised financial advice. Returns and tax treatment vary, so consult a SEBI-registered advisor for your situation.