Sandwich generation: Caring for ageing parents, funding children’s dreams; are you sacrificing your retirement savings?
1/8
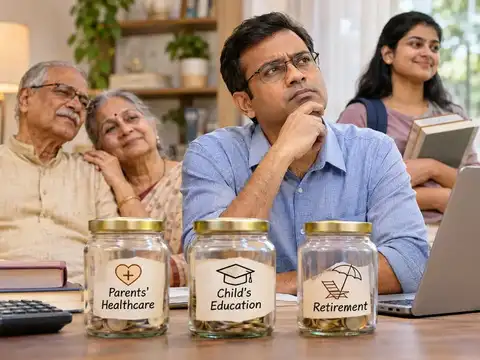
Your children need you. Your parents need you. But what about your retirement?
You are paying your child's education fees, helping your parents manage medical bills and keeping the household running. Every month, a large part of your salary goes towards someone else's needs.
Your retirement, meanwhile, keeps getting pushed to another year.
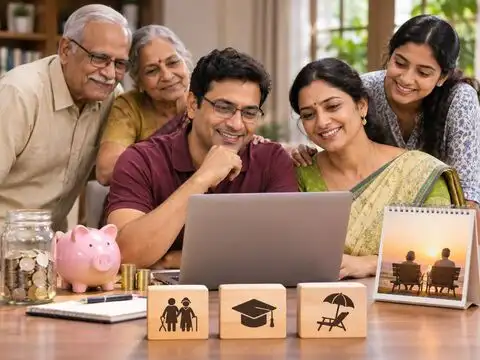
This is the financial squeeze faced by India's sandwich generation: middle-aged earners supporting their children while also caring for ageing parents. The challenge is to meet today's responsibilities without sacrificing tomorrow's financial security.
Your retirement, meanwhile, keeps getting pushed to another year.
This is the financial squeeze faced by India's sandwich generation: middle-aged earners supporting their children while also caring for ageing parents. The challenge is to meet today's responsibilities without sacrificing tomorrow's financial security.
2/8
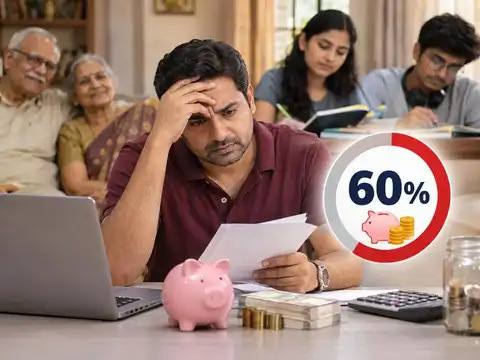
60% feel their savings will never be enough
The financial pressure on India's sandwich generation is significant.
An Edelweiss Life Insurance study conducted with YouGov, covering 4,005 respondents aged 35-54 across 12 cities, found that 60% felt their savings and investments would never be enough for their future.
The study also found that 64% relied on credit, loans or buy-now-pay-later options to fund short-term aspirations.
This highlights a worrying reality: even people who earn and save regularly can struggle to balance immediate family expenses with long-term financial goals.
An Edelweiss Life Insurance study conducted with YouGov, covering 4,005 respondents aged 35-54 across 12 cities, found that 60% felt their savings and investments would never be enough for their future.
The study also found that 64% relied on credit, loans or buy-now-pay-later options to fund short-term aspirations.
This highlights a worrying reality: even people who earn and save regularly can struggle to balance immediate family expenses with long-term financial goals.
3/8
Two generations need money at the same time
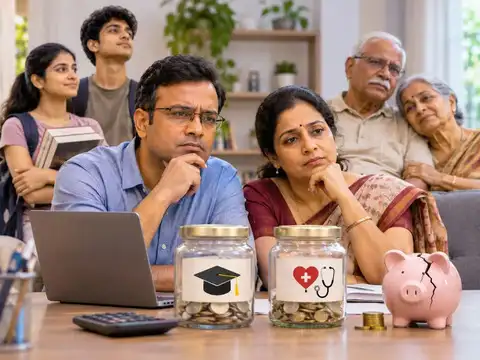
For middle-aged earners, financial responsibilities often come from both directions.
Children need money for school fees, coaching, higher education and accommodation. At the same time, ageing parents may need regular medicines, medical tests, hospitalisation or assistance with everyday expenses.
An Edelweiss Life study found that 46% of respondents worried about their children's education costs, while 43% were concerned about future healthcare expenses.
When both generations depend on the same income, retirement savings often become the first casualty.
Children need money for school fees, coaching, higher education and accommodation. At the same time, ageing parents may need regular medicines, medical tests, hospitalisation or assistance with everyday expenses.
An Edelweiss Life study found that 46% of respondents worried about their children's education costs, while 43% were concerned about future healthcare expenses.
When both generations depend on the same income, retirement savings often become the first casualty.
4/8
A small withdrawal today can create a big retirement gap
Taking money out of long-term investments may solve an immediate family problem, but it can create a much bigger financial challenge later.
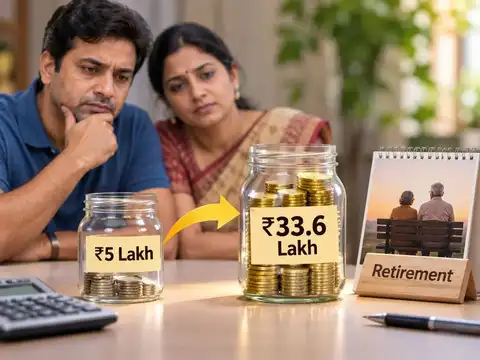
Consider this example: If you withdraw ₹5 lakh from your retirement investments today, you also give up the opportunity for that money to grow over the next 20 years.
At an assumed annual return of 10%, that ₹5 lakh could have grown to approximately ₹33.6 lakh over two decades.
The difference is significant. You are not just losing the amount withdrawn; you are also losing the potential returns it could have generated through compounding.
Repeated withdrawals for children's education, parents' medical bills or other family commitments can weaken your retirement corpus, even if you continue investing.
The takeaway: Your retirement savings should not become the family's default emergency fund.
Note: This is an illustration based on 10% annual compounding. Actual investment returns are not guaranteed and may vary.
Consider this example: If you withdraw ₹5 lakh from your retirement investments today, you also give up the opportunity for that money to grow over the next 20 years.
At an assumed annual return of 10%, that ₹5 lakh could have grown to approximately ₹33.6 lakh over two decades.
The difference is significant. You are not just losing the amount withdrawn; you are also losing the potential returns it could have generated through compounding.
Repeated withdrawals for children's education, parents' medical bills or other family commitments can weaken your retirement corpus, even if you continue investing.
The takeaway: Your retirement savings should not become the family's default emergency fund.
Note: This is an illustration based on 10% annual compounding. Actual investment returns are not guaranteed and may vary.
5/8
Parents' medical bills can become a retirement risk
Healthcare is one of the biggest financial uncertainties for families supporting ageing parents.
A SEBI-hosted industry report citing Frost & Sullivan estimated India's average healthcare inflation at 10.8% between 2018 and 2024, reaching 14% in 2024.
Regular medicines, consultations, diagnostic tests and hospitalisation can quickly increase family expenses.
Review your parents' health insurance, including waiting periods, exclusions, co-payments and coverage limits. Build a separate medical emergency fund for expenses that insurance may not cover.
Planning ahead can prevent a medical emergency from becoming a retirement crisis.
A SEBI-hosted industry report citing Frost & Sullivan estimated India's average healthcare inflation at 10.8% between 2018 and 2024, reaching 14% in 2024.
Regular medicines, consultations, diagnostic tests and hospitalisation can quickly increase family expenses.
Review your parents' health insurance, including waiting periods, exclusions, co-payments and coverage limits. Build a separate medical emergency fund for expenses that insurance may not cover.
Planning ahead can prevent a medical emergency from becoming a retirement crisis.
6/8
Supporting children should not mean funding every expense
Parents naturally want to provide the best opportunities for their children. But funding every financial need can put retirement plans under pressure.
Prioritise essential expenses such as education, but encourage older children to explore scholarships, education loans where appropriate and part-time opportunities.
Help them develop budgeting and saving habits instead of depending entirely on parental support.
Avoid taking excessive loans or withdrawing retirement investments to finance lifestyle upgrades and discretionary expenses.
Helping children become financially independent is also an important part of parenting.
Prioritise essential expenses such as education, but encourage older children to explore scholarships, education loans where appropriate and part-time opportunities.
Help them develop budgeting and saving habits instead of depending entirely on parental support.
Avoid taking excessive loans or withdrawing retirement investments to finance lifestyle upgrades and discretionary expenses.
Helping children become financially independent is also an important part of parenting.
7/8
Five money moves to protect your retirement
Supporting two generations requires a clear financial plan. Here are five steps to protect your future.
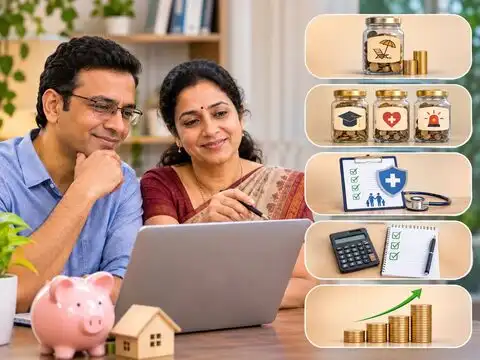
1. Invest before spending: Automate retirement contributions as soon as your salary arrives.
2. Create separate funds: Maintain dedicated savings for children's education, parents' healthcare and emergencies.
3. Review insurance: Check health coverage for your parents and family, along with your own life insurance.
4. Set financial boundaries: Decide how much you can comfortably contribute towards family expenses.
5. Increase retirement investments: Redirect money towards retirement when education loans end or children become financially independent.
1. Invest before spending: Automate retirement contributions as soon as your salary arrives.
2. Create separate funds: Maintain dedicated savings for children's education, parents' healthcare and emergencies.
3. Review insurance: Check health coverage for your parents and family, along with your own life insurance.
4. Set financial boundaries: Decide how much you can comfortably contribute towards family expenses.
5. Increase retirement investments: Redirect money towards retirement when education loans end or children become financially independent.
8/8
Your family needs your support. Your future needs a plan.
The sandwich generation often measures financial success by how much it can provide for its family. But supporting loved ones should not mean sacrificing your own financial security.
Your parents deserve care, and your children deserve opportunities. Your retirement deserves a place in the family budget, too.
Calculate your retirement needs, review your existing investments and set a realistic monthly savings target. Increase contributions as your income grows.
You have spent years building a secure future for your family. Make sure you have one waiting for yourself, too.
Your parents deserve care, and your children deserve opportunities. Your retirement deserves a place in the family budget, too.
Calculate your retirement needs, review your existing investments and set a realistic monthly savings target. Increase contributions as your income grows.
You have spent years building a secure future for your family. Make sure you have one waiting for yourself, too.