NPS Tier 1 vs Tier 2: Which account saves more tax? Key differences every investor must know
1/8
One pension scheme, two accounts that work completely differently
The National Pension System is a government-backed retirement scheme open to any Indian citizen, NRI, or OCI between 18 and 70, and it lets you invest across equity, corporate bonds, and government securities to build a retirement corpus. But here's what most people miss: NPS isn't one account, it's two. Tier 1 is the mandatory, lock-in retirement account. Tier 2 is a voluntary add-on that behaves more like a flexible savings account. You can't open Tier 2 without first having an active Tier 1, and confusing the two can mean missing out on either serious tax savings or serious liquidity.
2/8
Tier 1 locks your money until you're 60, Here's why that's the point
Tier 1 is the core retirement account, and its defining feature is discipline: your money is locked in until you turn 60, with a minimum contribution of just Rs 1,000 a year to keep it active. That lock-in isn't a downside, it's the entire mechanism that forces long-term wealth building instead of impulsive withdrawals. Partial withdrawals are allowed, but only for specific situations like critical illness, higher education, or buying a home, and even then, only up to four times at 25% each over the account's lifetime.
3/8
The tax deduction most salaried employees are leaving on the table
Tier 1 contributions can unlock some of the most generous tax deductions available under Indian tax law. Under the old regime, you can claim up to Rs 1.5 lakh under Section 80C plus an additional Rs 50,000 under Section 80CCD(1B), a benefit that goes beyond what most other retirement instruments offer. Even under the new tax regime, where personal deductions largely disappear, employer contributions of up to 14% of your basic salary remain deductible under Section 80CCD(2). That single clause means Tier 1 tax savings survive even after regime changes that eliminated most other deductions.
Amazon Top Deals
POWERED BY
4/8
Tier 2 has zero lock-in, and that changes everything
Tier 2 flips the entire model: there's no lock-in period, no mandatory annual contribution, and you can withdraw your money any time you want, for any reason. It's essentially a market-linked investment account riding on the same NPS infrastructure, minimum management costs, no exit load, and full access to your funds whenever you need them. The tradeoff is real, though: Tier 2 offers no general tax benefits, and any returns you withdraw get taxed at your regular income slab rate.
5/8
Which account actually lets you go 100% equity?
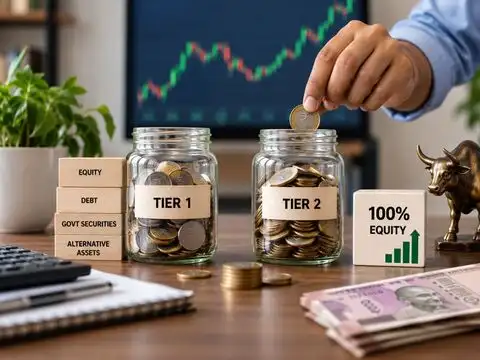
Here's a detail that surprises a lot of investors: Tier 2 allows up to 100% allocation into equity, while Tier 1's standard scheme caps equity exposure at 75%, though certain plans permit higher limits. Tier 1 also opens the door to alternative assets, up to 5% under Scheme A, an option Tier 2 doesn't offer at all. So depending on your risk appetite, the "flexible" account might actually let you take on more market risk than the "retirement-focused" one.
6/8
What happens to your money the day you turn 60
When Tier 1 matures, the rules get specific fast. If your corpus is above Rs 12 lakh, you can withdraw up to 80% as a lump sum, though only 60% of the total corpus is tax-free under current law, and the rest must go toward buying an annuity for regular income. If your corpus is under Rs 8 lakh, you can withdraw the entire amount at once. Tier 2 works completely differently at this stage: there's no special maturity event and no "60% tax-free" status. Withdrawals simply get added to your taxable income whenever you make them.
7/8
Why smart investors don't choose one account, they use both
The real strategy many experienced NPS investors land on isn't Tier 1 versus Tier 2, it's Tier 1 and Tier 2 together. Tier 1 handles the disciplined, tax-advantaged retirement build-out you can't touch until 60. Tier 2 becomes the flexible layer for short-term goals, emergency access, or simply parking money in a low-cost, market-linked account without a lock-in. You can even transfer funds from Tier 2 into Tier 1 later to claim additional tax benefits, effectively using Tier 2 as a staging area before committing money to the long-term account.
8/8
The simple question that decides which account you actually need
Before opening either account, ask one question: do you need this money to be untouchable, or accessible? If the answer is "I want disciplined retirement savings and I'm fine not touching it for decades," Tier 1 is the clear choice, especially with its tax deductions attached. If the answer is "I want market-linked growth but need to be able to access my money anytime," Tier 2 fits better, minus the tax perks. And if you genuinely want both discipline and flexibility, there's nothing stopping you from running both accounts side by side under the same PRAN.