Freelancer vs consultant vs business owner: How income tax rules differ and what you need to know before filing ITR
1/9
Self-employed? Here's your complete tax guide
This year’s ITR filing days are nearly over but here’s something you should always keep in mind. If you earn money from a business, freelance work, or a profession instead of a regular salary, the tax rules are different — and it's on you to get them right. Here's everything you need to know, simplified.
2/9
Are you actually "self-employed" in the eyes of the law?
It's not just shop owners and consultants. Doctors, lawyers, freelancers, content creators, commission agents, and sole proprietors all fall under this category. Your income gets taxed under "Profits and Gains of Business or Profession" — a completely different head than salaried income.
3/9
You have 2 options for paying tax
Option one: the presumptive scheme, where you skip listing expenses and pay tax on a fixed percentage of income. Option two: the real profit method, where you deduct actual expenses first, then pay tax on what's left. Your turnover often decides which one you can use.
Amazon Top Deals
POWERED BY
4/9
Filing the wrong form could cost you
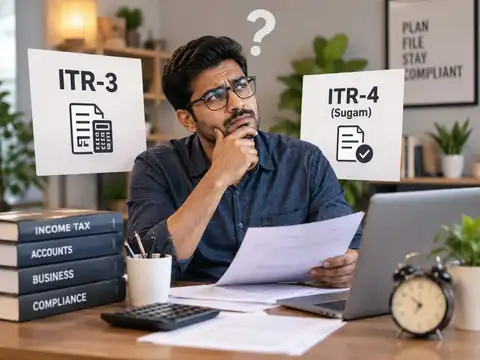
Self-employed taxpayers usually file ITR-3 or ITR-4. ITR-3 is for those maintaining full books of accounts. ITR-4 (Sugam) is for those under the presumptive scheme. Picking the wrong one is one of the most common, and costly, filing mistakes.
5/9
The easy way out: Presumptive Taxation
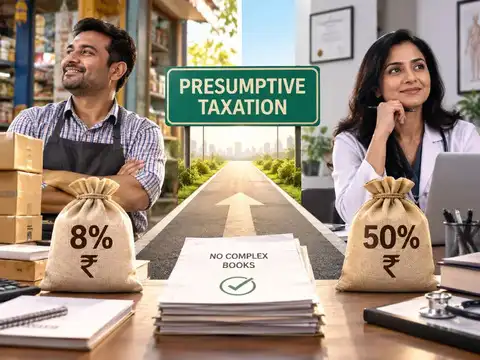
If your turnover is under ₹2 crore, you can skip detailed bookkeeping. Business owners are assumed to earn 8% profit on receipts; professionals are assumed to earn 50%. Tax is calculated on that assumed income — no expense proof needed.
6/9
The real profit method or claim every rupee you spent
Prefer accuracy over simplicity? Deduct rent, salaries, travel, internet bills, and loan interest from your income, then pay tax only on real profit. Just keep proof of every expense — and if you earn over ₹50 lakh, a CA audit becomes mandatory.
7/9
Old Regime or New Regime: Which saves you more?
The new regime offers lower slab rates but blocks most deductions like 80C and 80D. The old regime has higher rates but lets you claim insurance premiums, home loan interest, and investment deductions. Run the numbers both ways before you decide.
8/9
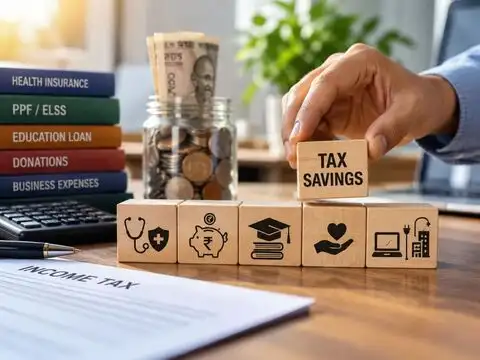
Don't leave money on the table
Health insurance premiums, PPF and ELSS investments, education loan interest, donations, and office expenses like rent, software, and electricity can all lower your tax bill — but only if you remember to claim them and choose the right regime.
9/9
5 mistakes that trigger tax notices
Wrong ITR form, underreported income, missing deductions, poor record-keeping, and late filing are the top reasons self-employed taxpayers get flagged. This year , you had to file it by August 31, keep your documents ready, and always verify your return after submitting.