Gold in wife’s name: Is it legal, tax-free and safe? 8 rules every Indian couple must know
1/8
Buying gold in your wife’s name? Yes, it’s legal. But read this first
Many Indian husbands buy gold in their wife’s name, hoping to keep things simple or save tax. There is no law that stops you from doing this. The trouble starts when the money behind the purchase cannot be explained, or when the gold is sold later and the tax is assessed in the wrong hands.
The Income-tax Department looks at who paid, how the money moved and who earns from the gold. This slideshow covers the rules on buying, gifting, selling, record keeping and how much gold you can hold at home without worry.
The Income-tax Department looks at who paid, how the money moved and who earns from the gold. This slideshow covers the rules on buying, gifting, selling, record keeping and how much gold you can hold at home without worry.
2/8
Her name on the bill does not settle whose money it is
If the gold is very expensive compared to your wife’s declared income, the tax department can send a notice asking where the money came from. That is true even if she is the one named on the invoice.
If you are paying, pay through the bank by net banking, account transfer or cheque, so there is a clear trail. Do not use large amounts of cash. Cash transactions of ₹2 lakh or more are restricted under Section 269ST, and a PAN card is needed for jewellery purchases above ₹2 lakh. Keeping the payment traceable is the simplest way to avoid questions later.
If you are paying, pay through the bank by net banking, account transfer or cheque, so there is a clear trail. Do not use large amounts of cash. Cash transactions of ₹2 lakh or more are restricted under Section 269ST, and a PAN card is needed for jewellery purchases above ₹2 lakh. Keeping the payment traceable is the simplest way to avoid questions later.
3/8
Gifting gold to your wife: Tax-free today, but not always tomorrow
A gift from a husband to a wife is not taxed in her hands, because a spouse counts as a relative under the law. But there is a catch called clubbing. If you give money or gold to your wife without any payment in return, any income or capital gain that comes from it can be added back to your income and taxed in your hands.
So if she sells that gifted gold at a profit, the gain may be taxed as yours, not hers. This is why it matters whether the gold was truly a gift or something she bought with her own earnings.
So if she sells that gifted gold at a profit, the gain may be taxed as yours, not hers. This is why it matters whether the gold was truly a gift or something she bought with her own earnings.
4/8
Her own money, her own gold: The cleanest way to buy
If your wife earns her own income, such as a salary, rent, a business or interest, and she pays for the gold from her own account, the purchase belongs to her and the clubbing rule does not apply to that gold.
Keep proof of her income and the payment from her bank account. The cleaner the paper trail, the less room there is for questions. If the gold was a gift from you, write it down in a gift deed or a simple signed declaration. It costs nothing and can save a long explanation in future.
Keep proof of her income and the payment from her bank account. The cleaner the paper trail, the less room there is for questions. If the gold was a gift from you, write it down in a gift deed or a simple signed declaration. It costs nothing and can save a long explanation in future.
5/8
Selling gold? Here is how much tax you will pay
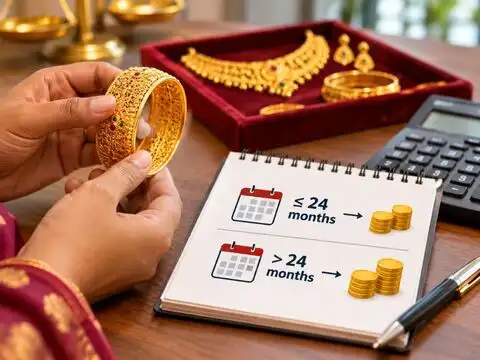
If you sell physical gold within 24 months of buying it, the profit is a short-term gain. It is added to your income and taxed at your slab rate. If you sell after 24 months, the profit is a long-term gain, taxed at 12.5% without the indexation benefit.
If the gold came as a gift or inheritance, your cost is the previous owner’s purchase cost. If they bought it before 1 April 2001, you can use its fair market value on that date, or the actual cost, whichever is higher. Some older articles still quote 36 months and 20.8% with indexation. Those were the old rules, so check the current ones before you sell.
If the gold came as a gift or inheritance, your cost is the previous owner’s purchase cost. If they bought it before 1 April 2001, you can use its fair market value on that date, or the actual cost, whichever is higher. Some older articles still quote 36 months and 20.8% with indexation. Those were the old rules, so check the current ones before you sell.
6/8
Sold your gold at a profit? You may be able to save the tax
Under Section 54F, an individual or HUF can claim an exemption on long-term gains from gold if the sale money is invested in a residential house. You must buy the house either one year before or two years after selling the gold. If you are building one, construction must finish within three years.
You should not own more than one other residential house on the date of sale. If you invest only part of the proceeds, you get a proportionate exemption. And if you sell the new house within three years, the exemption is withdrawn and the gain becomes taxable again that year.
You should not own more than one other residential house on the date of sale. If you invest only part of the proceeds, you get a proportionate exemption. And if you sell the new house within three years, the exemption is withdrawn and the gain becomes taxable again that year.
7/8
How much gold can you keep at home without trouble?
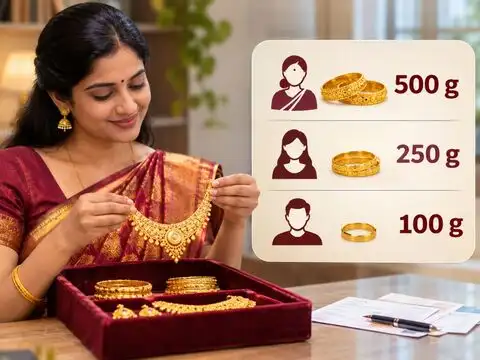
There is no limit on how much gold you can own if you can explain where it came from. The limits matter only during a search, when the gold has no proof of source. In that case, officers generally do not seize up to 500 grams for a married woman, 250 grams for an unmarried woman and 100 grams for a man.
These are administrative guidelines, not a legal cap, and paperwork matters more than weight. Gold bought with proper bills and bank payments is safe at any quantity. Gold with no proof can be questioned even if it is under the limit.
These are administrative guidelines, not a legal cap, and paperwork matters more than weight. Gold bought with proper bills and bank payments is safe at any quantity. Gold with no proof can be questioned even if it is under the limit.
8/8
Your gold paperwork checklist: Keep these for years
Keep the original purchase bills and invoices, with the jeweller’s name and the weight and purity written clearly. Keep bank statements or cheque records that show how you paid. If gold was gifted, keep the gift deed or a signed note. For inherited gold, keep a will, family settlement or any document showing who it came from.
Remember the costs on the bill too. GST is charged at 3% on gold and 5% on making charges, but there is no GST when you sell. Store everything in one folder, or take photos on your phone. You will need it when you sell, take a gold loan or face a tax query.
This is general information, not personalised tax advice. Talk to a chartered accountant before making large purchases or sales.
Remember the costs on the bill too. GST is charged at 3% on gold and 5% on making charges, but there is no GST when you sell. Store everything in one folder, or take photos on your phone. You will need it when you sell, take a gold loan or face a tax query.
This is general information, not personalised tax advice. Talk to a chartered accountant before making large purchases or sales.