Retirement planning: 3 budgets you must prepare before you retire
1/8
Retirement is not just about how much you save
A large retirement corpus may look reassuring, but it does not automatically guarantee financial security. What matters is how well you manage that money once your regular salary stops.
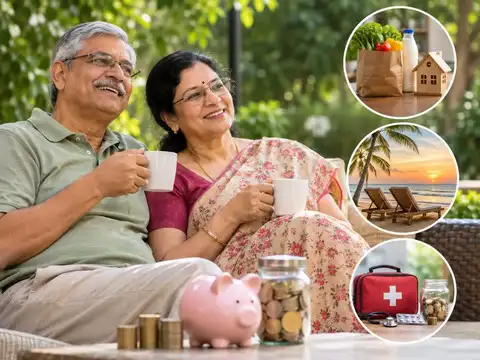
Before retiring, it helps to divide your finances into three separate budgets: one for essential expenses, another for the lifestyle you want to maintain and a third for unexpected costs. This simple approach can help you spend with confidence without putting your long-term savings under unnecessary pressure.
Before retiring, it helps to divide your finances into three separate budgets: one for essential expenses, another for the lifestyle you want to maintain and a third for unexpected costs. This simple approach can help you spend with confidence without putting your long-term savings under unnecessary pressure.
2/8
Budget 1 – Your everyday living expenses
Your first budget should cover the expenses you cannot avoid, regardless of market conditions or lifestyle changes.
Start by calculating your monthly spending on groceries, electricity, household bills, cooking gas, transportation, medicines, insurance premiums and other essential payments. Include housing costs, maintenance charges and any outstanding loan EMIs.
Do not simply use your current monthly expenses as a benchmark. Some costs may fall after retirement, while healthcare and household support expenses could increase. Estimate what you will actually need every month and account for inflation.
Start by calculating your monthly spending on groceries, electricity, household bills, cooking gas, transportation, medicines, insurance premiums and other essential payments. Include housing costs, maintenance charges and any outstanding loan EMIs.
Do not simply use your current monthly expenses as a benchmark. Some costs may fall after retirement, while healthcare and household support expenses could increase. Estimate what you will actually need every month and account for inflation.
3/8
Calculate how much your basic needs will cost
Suppose your household currently spends ₹40,000 a month on essential expenses. That amounts to ₹4.8 lakh a year.
However, retirement could change this calculation. Medical costs may rise, utility bills may increase and you may spend more time at home. On the other hand, commuting and work-related expenses could disappear.
Prepare a realistic monthly estimate rather than assuming your current spending will remain unchanged. This figure will help you determine how much of your pension, annuity or investment income must be available to cover essential expenses.
However, retirement could change this calculation. Medical costs may rise, utility bills may increase and you may spend more time at home. On the other hand, commuting and work-related expenses could disappear.
Prepare a realistic monthly estimate rather than assuming your current spending will remain unchanged. This figure will help you determine how much of your pension, annuity or investment income must be available to cover essential expenses.
4/8
Budget 2 – The lifestyle you want to enjoy
Retirement should not mean giving up everything you enjoy. Your second budget should make room for the experiences and activities that give you a sense of freedom.
Set aside money for holidays, family visits, hobbies, eating out, entertainment, festivals, gifts and occasional purchases. If you plan to travel more frequently or support your grandchildren, include those expenses too.
The important thing is to decide how much you can comfortably spend without disturbing the money reserved for essential expenses. A separate lifestyle budget also helps prevent discretionary spending from eating into your long-term retirement savings.
Set aside money for holidays, family visits, hobbies, eating out, entertainment, festivals, gifts and occasional purchases. If you plan to travel more frequently or support your grandchildren, include those expenses too.
The important thing is to decide how much you can comfortably spend without disturbing the money reserved for essential expenses. A separate lifestyle budget also helps prevent discretionary spending from eating into your long-term retirement savings.
5/8
Give your lifestyle budget a reality check
A common retirement planning mistake is assuming that every month will cost roughly the same.
Some months may involve only routine spending, while others could bring a family wedding, a holiday, home renovations or a major purchase.
Instead of treating these as unexpected expenses, plan for them in advance. Estimate your annual lifestyle spending and divide it into a monthly savings target.
This gives you room to enjoy retirement while keeping your spending under control. If investment returns are lower than expected, lifestyle expenses are also easier to adjust than essential household costs.
Some months may involve only routine spending, while others could bring a family wedding, a holiday, home renovations or a major purchase.
Instead of treating these as unexpected expenses, plan for them in advance. Estimate your annual lifestyle spending and divide it into a monthly savings target.
This gives you room to enjoy retirement while keeping your spending under control. If investment returns are lower than expected, lifestyle expenses are also easier to adjust than essential household costs.
6/8
Budget 3 – Prepare for emergencies and unexpected expenses
Your third budget is your financial safety net. It should cover expenses that are difficult to predict but can seriously affect your retirement savings.
These may include hospitalisation, medical procedures, home repairs, urgent family support, insurance deductibles and other unforeseen costs.
Maintain an accessible emergency reserve instead of depending entirely on investments that may be volatile or difficult to liquidate at short notice. The size of this reserve should reflect your health needs, insurance coverage, dependants and regular expenses.
Also review your health insurance before retirement. Employer-provided medical cover may end when you leave your job, so check what protection will remain available.
These may include hospitalisation, medical procedures, home repairs, urgent family support, insurance deductibles and other unforeseen costs.
Maintain an accessible emergency reserve instead of depending entirely on investments that may be volatile or difficult to liquidate at short notice. The size of this reserve should reflect your health needs, insurance coverage, dependants and regular expenses.
Also review your health insurance before retirement. Employer-provided medical cover may end when you leave your job, so check what protection will remain available.
7/8
Keep your retirement income and expenses in sync
Once your three budgets are ready, compare them with your expected retirement income.
List all your potential income sources, including EPF, PPF, NPS, pension payments, annuities, rental income, interest and withdrawals from mutual funds or other investments.
Make sure reliable income sources can meet a substantial part of your essential expenses. Plan your remaining withdrawals carefully, keeping inflation, taxes, investment risks and your expected retirement period in mind.
Do not assume that a fixed monthly withdrawal will remain sustainable forever. Review your income and expenses at least once a year and adjust your plan when circumstances change.
List all your potential income sources, including EPF, PPF, NPS, pension payments, annuities, rental income, interest and withdrawals from mutual funds or other investments.
Make sure reliable income sources can meet a substantial part of your essential expenses. Plan your remaining withdrawals carefully, keeping inflation, taxes, investment risks and your expected retirement period in mind.
Do not assume that a fixed monthly withdrawal will remain sustainable forever. Review your income and expenses at least once a year and adjust your plan when circumstances change.
8/8
A comfortable retirement starts with three clear budgets
You do not need to stop enjoying life to protect your retirement savings. You need a plan that tells you what you can spend, what you should preserve and what you must keep aside for emergencies.
Keep your essential expenses covered, give yourself a realistic lifestyle allowance and maintain a separate emergency reserve. Review these budgets whenever healthcare costs, inflation, family responsibilities or investment income change.
The goal is not simply to retire with a large corpus. It is to make that corpus last while giving you the financial freedom to enjoy the years ahead.
Keep your essential expenses covered, give yourself a realistic lifestyle allowance and maintain a separate emergency reserve. Review these budgets whenever healthcare costs, inflation, family responsibilities or investment income change.
The goal is not simply to retire with a large corpus. It is to make that corpus last while giving you the financial freedom to enjoy the years ahead.