Financial planning for DINK couples in India: 10 money moves for two incomes
1/11
Two salaries. no kids. So why aren’t you rich yet?
“You must be saving a fortune.” Sound familiar? If you are a DINK couple (Dual Income, No Kids), people assume you are winning at money. But two incomes do not automatically build wealth. The advantage only shows up when you plan well. Here is how to turn flexibility into real financial freedom.
2/11
Are you DINK for now or DINK for life?
Not every DINK couple has the same plan. Some will stay child-free for good. Others want kids later, and are called DINKY (double income, no kids yet). The difference matters. A couple that stays child-free may fund travel, early retirement and healthcare. A couple planning a child may need money for childcare and education. Decide what your surplus may need to fund, and keep your plan flexible.
3/11
Earning more is not the same as building more
Lifestyle inflation is the biggest DINK trap. Bigger homes, premium cars and frequent holidays all feel affordable on two salaries. Here is the proof: a couple earning ₹3 lakh a month but investing ₹30,000 can end up with less wealth than a couple earning ₹2 lakh and investing ₹70,000 steadily. What you consistently turn into assets matters more than what you earn.
4/11
Know your number: The ₹1 lakh surplus test
Start with your combined cash flow. Say your take-home is ₹2,50,000, essentials cost ₹90,000 and lifestyle spending is ₹60,000. Your surplus is ₹1,00,000. That is the money that can build your future. You do not need to merge every bank account, but both partners should know about expenses, loans, investments, insurance, nominations and documents. Financial independence is healthy. Financial secrecy is not.
5/11
Two salaries still need an emergency fund and real insurance
Having two incomes does not remove the need for a safety net. Build an emergency reserve based on your actual costs, such as EMIs, rent, groceries, premiums and medical bills. Review personal health insurance too, because employer cover can end when you switch jobs, take a break or retire. For life insurance, ask one question: if one income vanished tomorrow, would someone face a serious financial problem?
6/11
Give every goal a price tag and a deadline
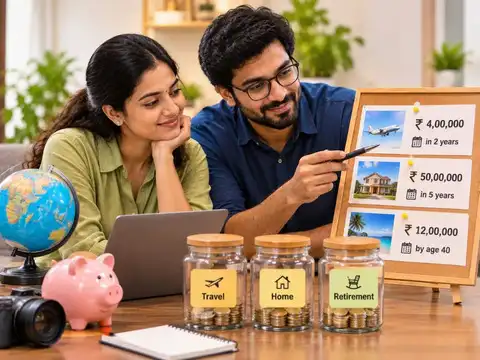
“We want to travel more” is a wish. “We want to spend ₹4 lakh a year on travel” is a plan. “We may take a career break” becomes “We want 12 months of expenses saved by age 40.” Once a goal has an amount and a timeline, you can work out how much to invest each month. Give each part of your portfolio a purpose instead of holding one big pile called “investments.”
7/11
Send your raise to work, not just to the mall
When your income grows, split the increase. Say your household income rises by ₹40,000 a month. You could spend ₹20,000 more on lifestyle and raise your monthly investment from ₹70,000 to ₹90,000. You still enjoy part of the raise, while the rest compounds for decades. Match your investments to each goal’s timeline, since short-term money cannot absorb market swings the way long-term money can.
8/11
The uncomfortable test: What if one income stops?
Imagine your household earns ₹4 lakh a month and spends ₹1.8 lakh. If one partner’s ₹2 lakh income stops, your surplus shrinks from ₹2.2 lakh to just ₹20,000. Run this test before you buy a home too. Bank eligibility is not the same as affordability. A big EMI that needs both salaries can wipe out the very flexibility that makes DINK life strong.
9/11
Plan for age 80, not just age 60
Retiring early, as in FIRE (Financial Independence, Retire Early), does not start with a magic number like ₹5 crore. It starts with the lifestyle you want. Work from your yearly expenses, retirement age, inflation and how long the money must last. Spending ₹12 lakh a year today will not be enough at 50. Also budget for later-life costs such as caregiving, home assistance, assisted living and medical support.
10/11
No kids doesn’t mean no dependants
Many DINK couples support parents through monthly transfers, medical bills, insurance or caregiving. A ₹25,000 monthly contribution adds up to ₹3 lakh a year and ₹15 lakh over five years, before any increases. Treat it as a planned commitment, not a withdrawal from investments. Decide how long support may last, which partner is responsible and how it affects your own retirement goals.
11/11
Who gets your wealth? Don’t leave it to chance
Without children, your wishes need to be even clearer. You may want assets to go to a spouse, parents, siblings or charity. Make a Will, update nominations and beneficiaries, and make sure ownership matches your wishes. Also plan for incapacity: if one partner cannot manage money, could the other find the bank details, policies, property papers and tax records? Review your full plan whenever life changes.
This is general educational information, not personalised investment, tax, insurance or legal advice. Examples are illustrative. Consult a SEBI-registered advisor for your situation.
This is general educational information, not personalised investment, tax, insurance or legal advice. Examples are illustrative. Consult a SEBI-registered advisor for your situation.