Baby on board? The ₹1-crore money plan and 8 money moves every new parent in India needs
1/9
Baby on board? The ₹1- crore money plan for new parents
Having a child changes your family’s net worth in three ways. There are direct costs, a shift in your career and savings momentum, and some long-term planning advantages.
Many financial planners suggest a target corpus of ₹1 crore to ₹1.25 crore per child. That covers education, milestones and marriage.
India’s life insurance penetration fell to 2.7% in FY 2024-25, the third straight year of decline, even though premium collections rose 7%. That leaves many growing families underinsured.
This guide covers the budget, insurance and investments you need in place early.
2/9
Your child could cost ₹1 crore+. Here’s where it goes
Milestone expenses. Raising a child in urban or semi-urban India takes a big financial commitment. Education, milestones and marriage together drive the ₹1 crore to ₹1.25 crore target.
Education and extras. School fees, higher education (engineering, medical or management degrees) and coaching classes are the largest recurring cash outflows. Education and healthcare inflation also run well ahead of general inflation.
Early childhood costs. Pediatric care, vaccinations, child-proofing and daily upkeep create immediate cash needs. That is why a dedicated emergency fund matters so much.
Delivery bills and nursery setup arrive at the same time as recurring costs like formula, diapers and daycare.
3/9
The hidden cost: Slower income, stronger savings drive
The short-term hit. Career breaks or reduced work hours can slow income growth and compounding in the early years. This is especially true for mothers in dual-income households.
The long-term push. Economic research points the other way over time. Providing for children often works as a psychological catalyst. Parents tend to work harder, advance their careers and stay disciplined about saving.
The takeaway is to plan for the early dip in income. Then lock in your savings habit before life gets busy.
4/9
India’s tax edge: Gift to your kids without the tax headache
Gifts between family: Unlike the US, where gifts to adult children trigger strict reporting and limits, Indian tax law allows tax-free cash gifts and financial support between close family members such as parents and children.
Generational planning: Indian parents often help adult children with a home, a vehicle or education loan repayments, with no direct tax penalty. The catch is that this can shrink your own liquid net worth if you don’t balance it against retirement needs.
Structuring tools: A Hindu Undivided Family (HUF), a properly drafted will, or a trust can pass wealth across generations tax-efficiently.
5/9
Budget first, emergency fund next
Step 1: Build a realistic baby budget before the baby arrives. Split costs into two buckets, because each needs a different funding plan.
One-time costs: delivery charges, crib, car seat, stroller, baby monitor. Fund these from a short-term savings goal started during pregnancy.
Recurring costs: formula, diapers, daycare, pediatrician visits, vaccinations. Build these into your monthly budget and review them often.
Many parents find dining-out and entertainment spending shrinks naturally while healthcare and childcare grow. Revisit the budget monthly for the first year and keep a 10-15% buffer for surprises.
Step 2: Build an emergency fund before insurance or investments. Aim to cover 6 months of household expenses. Keep it in a savings account or liquid mutual fund you can reach within a day. That way a hospital stay or job change won’t force you to break long-term investments or borrow at high interest. Starting from zero? Automate a fixed monthly transfer, even ₹5,000-10,000.
6/9
Insure the whole family
Step 3: Get adequate life insurance. If something happens to you, your child’s education and daily life shouldn’t be at risk. A pure term plan gives the highest cover for the lowest premium. As a rule of thumb, aim for cover of 10-15 times your annual income. Revisit it when your income, liabilities or family size changes.
Step 4: Don’t skip health insurance for mother and baby. Private hospital stays can run into lakhs, and a basic employer policy often isn’t enough once dependents are added. Look for:
A family floater plan with a sum insured of ₹10 lakh or more, where affordable
Maternity and newborn cover, since many policies have a waiting period
Vaccination and day-care procedure cover for infants
Most insurers let you add a newborn within 90 days of birth. Check that clause before you need it.
7/9
Where to invest for your newborn
Time is a new parent’s biggest advantage. Even modest, steady investments compound a lot over 15-18 years.
Public Provident Fund (PPF): Suits any child and safety-first parents. About 7.1% a year, 15-year lock-in, tax-free and government-backed.
Sukanya Samriddhi Yojana (SSY): For a girl child under 10. About 8.2% a year, 21-year lock-in, the highest safe return, with a Section 80C benefit.
Mutual fund SIPs: For long-term growth over 12+ years. Returns are market-linked, with a flexible lock-in and inflation-beating potential.
Child insurance or ULIP plans: Protection and savings together. Returns depend on the plan, with life cover and payouts at milestones.
Rates are as notified for the April-June 2026 quarter and are revised every quarter. Check the India Post small savings page for the latest.
For most families, a mix works best. Use a government-backed instrument for safety, an SIP for growth, and a life-cover-linked plan so milestones are funded whatever the market does.
8/9
Don’t sacrifice your retirement for your child
Step 6: Protect your own future. You can borrow for a child’s education, but no one lends for retirement. Keep contributing to your EPF, NPS or PPF while you save for your baby. A modest automated contribution protects you from depending on your child later. Treat retirement and your child’s fund as two parallel goals, not rivals for the same rupee.
Step 7: Update your will and nominations. Every bank account, insurance policy, EPF account and mutual fund folio needs your child added as beneficiary or nominee. If you have no will, make one now. It sets out guardianship and asset handling clearly and avoids disputes.
Step 8: Plan for childcare and an income gap. In establishments with 10 or more employees, the Code on Social Security, 2020 gives eligible women 26 weeks of paid maternity leave for the first two children. Private-sector paternity leave isn’t mandated and varies by company. If a parent will take a long break, build that income gap into your budget early. Get local daycare prices early too, since good childcare books up months ahead.
9/9
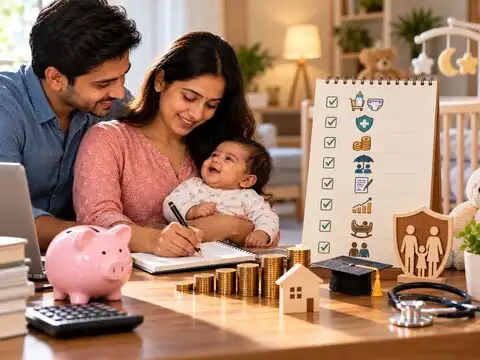
The new parent money checklist
Immediate priorities (first 1-3 months)
Baby budget (one-time and recurring costs) created. It prevents the early spending shock.
Newborn added to health insurance. Most insurers require this within 90 days of birth.
6-month emergency fund started. It cushions medical bills or an income gap.
Term life insurance reviewed or bought. It protects your child’s education and lifestyle.
Within the first year
Will and nominations updated, so guardianship and assets are handled as you intend.
Child investment plan (PPF, SSY or SIP) opened, because time in the market matters more than timing it.
Your own retirement contributions (EPF, NPS, PPF) kept going. Education loans exist for your child, but retirement loans don’t exist for you.
Childcare and income-gap plan finalised, to avoid a scramble when parental leave ends.
Keep this list somewhere visible and review it every quarter as your child grows.