Sensex crash survival guide: 10 moves to protect your savings, save tax and keep investing
1/10
Sensex down 10%? Here’s what the market words actually mean
A fall of 10% or more from a recent high is called a correction. A fall of 20% or more is a bear market. “Crash” has no official definition. It usually means a sudden, steep drop over a day or two, like the Sensex losing over 13% on 23 March 2020.
To stop panic spirals, SEBI has market-wide circuit breakers. If the Nifty or Sensex falls 10%, 15% or 20%, trading pauses or stops for the day, depending on the time of the fall. These labels only describe what has already happened. They don’t tell you what comes next, so don’t make decisions based on them alone.
To stop panic spirals, SEBI has market-wide circuit breakers. If the Nifty or Sensex falls 10%, 15% or 20%, trading pauses or stops for the day, depending on the time of the fall. These labels only describe what has already happened. They don’t tell you what comes next, so don’t make decisions based on them alone.
2/10
Don’t Stop that SIP. Your best buying happens when markets are red
When markets fall, many people pause their SIPs. That is exactly when your monthly amount buys the most units. A ₹10,000 SIP that buys 100 units at ₹100 NAV buys 125 units when the NAV drops to ₹80.
Over a long slump, this lowers your average cost. When the market finally turns, you hold more units to benefit from the recovery. Stopping your SIP means you skip the cheap months and then restart when prices feel “safe”, which is usually higher. If your income is steady and your emergency fund is in place, keep every instalment running. If you can afford it, a small top-up during the fall helps even more.
Over a long slump, this lowers your average cost. When the market finally turns, you hold more units to benefit from the recovery. Stopping your SIP means you skip the cheap months and then restart when prices feel “safe”, which is usually higher. If your income is steady and your emergency fund is in place, keep every instalment running. If you can afford it, a small top-up during the fall helps even more.
3/10
Money needed within 5 years should not be in equity
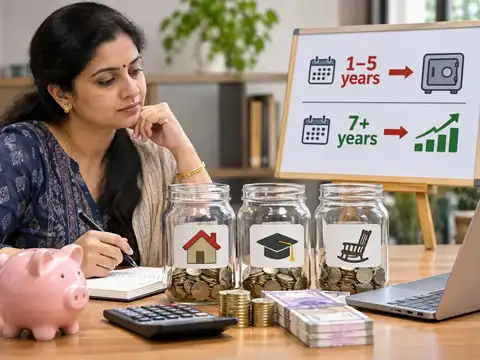
Write down each goal with a date and an amount. A house down payment next year, a child’s fees in two years, retirement in 25 years. Each one needs a different answer.
If you need the money within 1 to 5 years, it belongs in safer places like fixed deposits, debt funds or arbitrage funds. Shares offer no promise about where prices will be on the day you need cash. If your goal is 7 to 10 years or more away, a fall in your portfolio is a paper loss. You still own the same units. The loss only becomes real when you sell at a low price. Panic selling also forces a second decision, when to buy back, and no one rings a bell for that.
If you need the money within 1 to 5 years, it belongs in safer places like fixed deposits, debt funds or arbitrage funds. Shares offer no promise about where prices will be on the day you need cash. If your goal is 7 to 10 years or more away, a fall in your portfolio is a paper loss. You still own the same units. The loss only becomes real when you sell at a low price. Panic selling also forces a second decision, when to buy back, and no one rings a bell for that.
4/10
The 6 to 12 month safety net most Indians skip
An emergency fund lets you pay bills during a market fall without selling investments at a loss. Most planners suggest 6 months of essential expenses in India. Go closer to 12 months if you are self-employed, a freelancer, or the only earner in your family.
Count only essentials: rent or EMI, groceries, school fees, insurance premiums, electricity, fuel and loan instalments. Leave out dining out and holidays. Slumps and job losses often arrive together, so you may need the money exactly when your shares are down. Keep it in a savings account, a liquid fund or a short-term FD. Never keep it in equity. Breaking a long-term FD or taking a personal loan at high interest is a costly way to find cash.
Count only essentials: rent or EMI, groceries, school fees, insurance premiums, electricity, fuel and loan instalments. Leave out dining out and holidays. Slumps and job losses often arrive together, so you may need the money exactly when your shares are down. Keep it in a savings account, a liquid fund or a short-term FD. Never keep it in equity. Breaking a long-term FD or taking a personal loan at high interest is a costly way to find cash.
5/10
Rebalance, don’t react: Fix your equity-debt mix
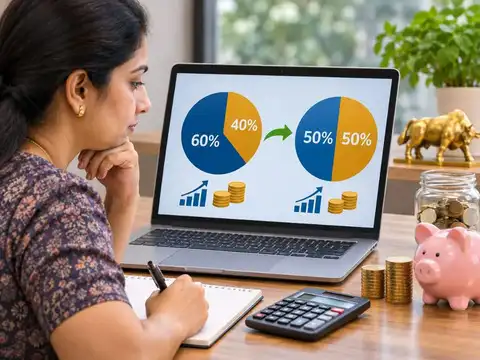
Say your plan was 60% equity and 40% debt. After a big fall, equity may shrink to 50%. Your portfolio is now less aggressive than you planned, without you choosing it.
Rebalancing means trimming what held up, like debt funds or gold, and moving that money into good equity funds at lower prices. It needs no prediction about the market bottom. It just brings your portfolio back to the risk level you picked in calmer times. You can rebalance once a year, or whenever an asset drifts more than 5 percentage points from its target. To avoid capital gains tax, point your new SIPs toward the underweight asset instead of selling. Balanced advantage and asset allocation funds do this automatically.
Rebalancing means trimming what held up, like debt funds or gold, and moving that money into good equity funds at lower prices. It needs no prediction about the market bottom. It just brings your portfolio back to the risk level you picked in calmer times. You can rebalance once a year, or whenever an asset drifts more than 5 percentage points from its target. To avoid capital gains tax, point your new SIPs toward the underweight asset instead of selling. Balanced advantage and asset allocation funds do this automatically.
6/10
Check the business, not just the share price
A falling price doesn’t always mean a bad company. Look at what is happening inside the business. Are profits still growing? Is debt under control? Is management honest and capable?
For each holding, ask why you bought it in the first place. If that reason still stands, a lower price may be an opportunity. If the reason has broken, such as permanently weaker earnings, rising debt, governance problems or a valuation that was always too high, then sell and move on. Holding on only out of hope is not a strategy. For mutual funds, check whether the fund is lagging its benchmark and category peers over 3 to 5 years, not just this quarter.
For each holding, ask why you bought it in the first place. If that reason still stands, a lower price may be an opportunity. If the reason has broken, such as permanently weaker earnings, rising debt, governance problems or a valuation that was always too high, then sell and move on. Holding on only out of hope is not a strategy. For mutual funds, check whether the fund is lagging its benchmark and category peers over 3 to 5 years, not just this quarter.
7/10
Turn your losses into a tax saving
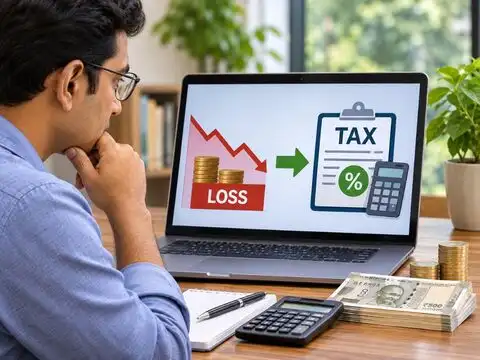
Selling a holding at a loss creates a capital loss that can cut your tax bill. Under current rules, short-term capital losses can be set off against both short-term and long-term gains. Long-term losses can only be set off against long-term gains. Unused losses can be carried forward for 8 years, but only if you file your return on time.
You can also do the reverse in a rising year. Equity long-term gains up to ₹1.25 lakh a year are tax free, so booking some gains and reinvesting can reset your purchase price. India has no formal wash-sale rule, but selling and rebuying the same share instantly purely for tax can draw questions. Tax rules change, so confirm current rates with a chartered accountant.
You can also do the reverse in a rising year. Equity long-term gains up to ₹1.25 lakh a year are tax free, so booking some gains and reinvesting can reset your purchase price. India has no formal wash-sale rule, but selling and rebuying the same share instantly purely for tax can draw questions. Tax rules change, so confirm current rates with a chartered accountant.
8/10
Retired? How to stop a crash from eating your corpus
A fall early in retirement hurts more than the same fall later. This is called sequence-of-returns risk. Every withdrawal during a slump means selling more units to get the same rupees, and those units are gone when the market recovers.
The fix is a bucket approach. Keep 2 to 3 years of expenses in FDs, liquid funds or short-term debt funds, and let equity recover untouched. A Systematic Withdrawal Plan from a debt or hybrid fund can give a steady monthly income. If you can, cut spending for a year or two by delaying a big purchase or skipping a raise in your monthly budget. Fewer units sold at low prices means a longer-lasting corpus.
The fix is a bucket approach. Keep 2 to 3 years of expenses in FDs, liquid funds or short-term debt funds, and let equity recover untouched. A Systematic Withdrawal Plan from a debt or hybrid fund can give a steady monthly income. If you can, cut spending for a year or two by delaying a big purchase or skipping a raise in your monthly budget. Fewer units sold at low prices means a longer-lasting corpus.
9/10
How safe is your money? What is and isn’t insured in India
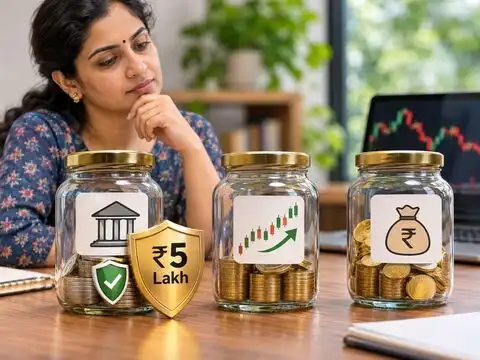
Bank deposits are insured by DICGC up to ₹5 lakh per depositor, per bank, covering principal and interest combined. Anything above that is not covered. If you hold large sums, spreading them across banks is worth considering.
Shares and mutual fund units work differently. Your shares sit in your own demat account with a depository like CDSL or NSDL, not with your broker. A broker going bust does not wipe out your holdings. Mutual fund assets are held by a separate custodian under SEBI rules. But none of this protects you from market losses. Insurance covers failure of an institution, not a fall in prices.
Shares and mutual fund units work differently. Your shares sit in your own demat account with a depository like CDSL or NSDL, not with your broker. A broker going bust does not wipe out your holdings. Mutual fund assets are held by a separate custodian under SEBI rules. But none of this protects you from market losses. Insurance covers failure of an institution, not a fall in prices.
10/10
What past Indian crashes teach us (and what they don’t)
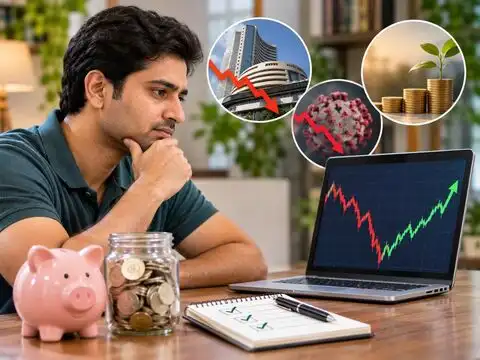
In 2008, the Sensex fell from about 21,000 in January to under 8,000 by October, a drop of roughly 60%. It took nearly three years to reclaim its old peak. In March 2020, it dropped around 38% in two months, then recovered to new highs within about eight months.
Two crashes, two very different recoveries. Investors who kept their SIPs running and avoided panic selling did far better than those who exited at the bottom. But past recoveries do not guarantee the next one will look the same. Make a plan now: list your goals, check your emergency fund, and decide your rules before the next fall.
This is general information, not personalised financial advice. Consider speaking to a SEBI-registered investment adviser or a chartered accountant for your situation.
Two crashes, two very different recoveries. Investors who kept their SIPs running and avoided panic selling did far better than those who exited at the bottom. But past recoveries do not guarantee the next one will look the same. Make a plan now: list your goals, check your emergency fund, and decide your rules before the next fall.
This is general information, not personalised financial advice. Consider speaking to a SEBI-registered investment adviser or a chartered accountant for your situation.