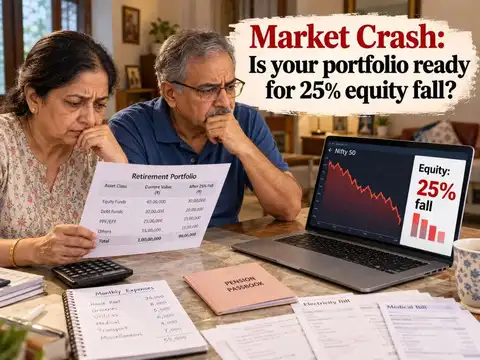
Retirement planning: Is your portfolio ready for a 25% stock market crash?
1/7
Market crash near retirement: Can your corpus withstand a 25% fall?
A 25% equity market crash can hurt retirees more than working investors, who can continue earning and investing through a downturn. Retirees may have to sell investments to meet expenses.
The five years around retirement matter most because of sequence-of-returns risk, says Akshat Garg, Head of Research & Product, Choice Wealth. The goal is to ensure your retirement lifestyle does not depend on how the market performs in a particular year.
The five years around retirement matter most because of sequence-of-returns risk, says Akshat Garg, Head of Research & Product, Choice Wealth. The goal is to ensure your retirement lifestyle does not depend on how the market performs in a particular year.
2/7
How much equity and debt should retirees hold?
There is no single equity-debt ratio for every retiree. The right mix depends on age, expenses, corpus, other income, risk appetite and retirement horizon. Swati Jain, CEO Wealth, Arihant Capital Markets, says an 80:20 equity-debt allocation may be too aggressive for most retirees and suggests 60:40 as a starting point, depending on individual circumstances.
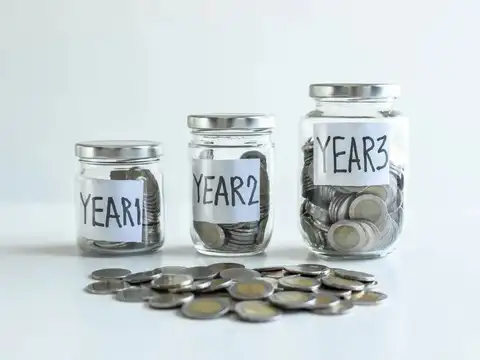
3/7
Keep 2–3 years of expenses outside equity
Jain suggests keeping two to three years of essential expenses in debt investments to avoid selling equity during a downturn. If monthly essential expenses are Rs 50,000:
● Two years’ expense: Rs 12 lakh
● Three years’ expense: Rs 18 lakh
Depending on their needs and risk profile, retirees could consider liquid funds, ultra-short-term funds or short-term fixed deposits. Keep this buffer separate from an emergency fund covering another six to 12 months of expenses.
● Two years’ expense: Rs 12 lakh
● Three years’ expense: Rs 18 lakh
Depending on their needs and risk profile, retirees could consider liquid funds, ultra-short-term funds or short-term fixed deposits. Keep this buffer separate from an emergency fund covering another six to 12 months of expenses.
4/7
How should you fund your SWP during a crash?
Think about Rs 1 crore saved for retirement. You take out Rs 50,000 every month using a systematic withdrawal plan (SWP). When the market corrects sharply, Jain suggests funding withdrawals from the debt part of your 60:40 equity-debt portfolio, instead of selling stocks. This way, the equity part of your portfolio will remain invested for a potential recovery.
However, if the downturn persists, continuing the same withdrawals without adjustments can put additional pressure on the retirement corpus.
However, if the downturn persists, continuing the same withdrawals without adjustments can put additional pressure on the retirement corpus.
5/7
Is a 3–4% annual withdrawal rate sustainable?
Akshat Garg suggests withdrawing 3–4% of the initial corpus annually as a broad starting point for a well-diversified retirement portfolio. However, no withdrawal rate guarantees that the corpus will last throughout retirement. The suitable rate depends on age, life expectancy, spending, inflation and asset allocation.
6/7
What should you do after a market crash?
Avoid panic selling. Garg says asset allocation should be decided before a crisis, not during one. For example, if your target allocation is 50:50 equity-debt, a market fall could shift it to 40:60. If your long-term strategy remains unchanged, consider rebalancing towards the original allocation rather than reacting emotionally to market movements.
7/7
Rebalance gradually instead of making sudden moves
Rebalancing does not require shifting a large amount from debt to equity immediately after a crash. Garg suggests gradually restoring the target allocation through future cash flows, interest income, maturing fixed-income investments and staggered deployment.
This keeps the portfolio aligned with the long-term plan without forcing abrupt decisions based on short-term market movements.
This keeps the portfolio aligned with the long-term plan without forcing abrupt decisions based on short-term market movements.