One fund or three Investments? Where should you put your ₹10 lakh?
1/8
One fund or three investments? Where should you put your ₹10 lakh in equity, gold and debt?
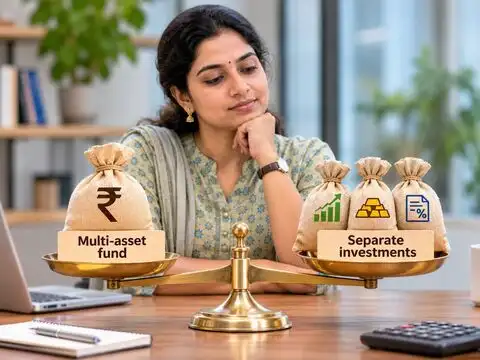
Equity can grow your wealth, debt can add stability and gold can diversify your portfolio. But should you combine all three through a multi-asset mutual fund or invest in each separately?
Both approaches offer diversification, but they differ in who controls your money, how often the portfolio gets rebalanced and how much flexibility you retain.
The right choice depends on your investment knowledge, discipline, tax situation and willingness to manage your portfol
Both approaches offer diversification, but they differ in who controls your money, how often the portfolio gets rebalanced and how much flexibility you retain.
The right choice depends on your investment knowledge, discipline, tax situation and willingness to manage your portfol
2/8
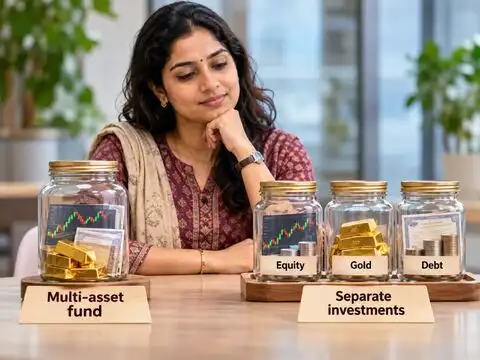
A multi-asset fund puts equity, debt and gold under one roof, but the fund manager decides the allocation
SEBI requires multi-asset allocation funds to invest in at least three asset classes, with a minimum allocation of 10% to each.
Most funds combine equities, fixed-income instruments and commodities such as gold and silver. Some also invest in other permitted asset classes.
The fund manager decides how much to allocate to each asset, based on the scheme's investment strategy and market outlook.
You get exposure to different asset classes through one mutual fund investment without having to manage separate holdings yourself.
Most funds combine equities, fixed-income instruments and commodities such as gold and silver. Some also invest in other permitted asset classes.
The fund manager decides how much to allocate to each asset, based on the scheme's investment strategy and market outlook.
You get exposure to different asset classes through one mutual fund investment without having to manage separate holdings yourself.
3/8
A ₹10 lakh portfolio can look similar under both approaches, but who manages the allocation makes the difference
Consider an illustrative portfolio with the following allocation:
Equity: ₹6 lakh (60%)
Gold: ₹2 lakh (20%)
Debt: ₹2 lakh (20%)
With a multi-asset fund, the fund manager manages the asset allocation within the scheme's mandate.
With separate investments, you could put ₹6 lakh into an equity mutual fund, ₹2 lakh into a gold ETF and ₹2 lakh into debt investments such as suitable debt funds or fixed deposits.
The starting allocation looks similar, but the investments are not identical. Their costs, tax treatment, underlying holdings and rebalancing methods can differ.
The real question is whether you want to manage these decisions yourself or delegate them to a fund manager.
Equity: ₹6 lakh (60%)
Gold: ₹2 lakh (20%)
Debt: ₹2 lakh (20%)
With a multi-asset fund, the fund manager manages the asset allocation within the scheme's mandate.
With separate investments, you could put ₹6 lakh into an equity mutual fund, ₹2 lakh into a gold ETF and ₹2 lakh into debt investments such as suitable debt funds or fixed deposits.
The starting allocation looks similar, but the investments are not identical. Their costs, tax treatment, underlying holdings and rebalancing methods can differ.
The real question is whether you want to manage these decisions yourself or delegate them to a fund manager.
4/8
Automatic rebalancing can save you effort, but it does not guarantee better returns
Suppose equity rises sharply and its share of your portfolio increases from 60% to 70%. Your portfolio is now taking more equity risk than originally planned.
A multi-asset fund manager can adjust the allocation according to the scheme's strategy, potentially booking profits in one asset and adding to another.
If you invest separately, you must decide when and how to rebalance. That means tracking your allocation and being disciplined enough to sell assets that have gained and add to those that have underperformed.
This is harder than it sounds. Investors often hesitate to sell winning investments or buy assets that have recently fallen.
Rebalancing helps manage portfolio risk; it does not ensure that you will earn higher returns.
A multi-asset fund manager can adjust the allocation according to the scheme's strategy, potentially booking profits in one asset and adding to another.
If you invest separately, you must decide when and how to rebalance. That means tracking your allocation and being disciplined enough to sell assets that have gained and add to those that have underperformed.
This is harder than it sounds. Investors often hesitate to sell winning investments or buy assets that have recently fallen.
Rebalancing helps manage portfolio risk; it does not ensure that you will earn higher returns.
5/8
Taxation can change the equation: a multi-asset fund does not automatically qualify for equity fund tax benefits
A multi-asset fund's tax treatment depends on its actual portfolio and whether it qualifies as an equity-oriented fund or falls under another tax category.
For qualifying equity-oriented funds:
*Short-term capital gains on units held for 12 months or less are generally taxed at 20%.
*Long-term capital gains are taxed at 12.5% on aggregate eligible gains exceeding ₹1.25 lakh in a financial year.
Separate investments have their own tax rules:
*Equity mutual funds generally follow equity-oriented fund taxation.
*Listed gold ETFs held for more than 12 months qualify for long-term capital gains treatment, generally at 12.5%, without the ₹1.25 lakh equity exemption.
*Gains from specified debt mutual funds acquired on or after April 1, 2023, are generally taxed at the investor's applicable income-tax slab rate, irrespective of the holding period.
A multi-asset fund that does not qualify for equity-oriented taxation may receive a different tax treatment.
Check the scheme's classification and current tax rules before investing. Tax can make a meaningful difference to your post-tax returns.
For qualifying equity-oriented funds:
*Short-term capital gains on units held for 12 months or less are generally taxed at 20%.
*Long-term capital gains are taxed at 12.5% on aggregate eligible gains exceeding ₹1.25 lakh in a financial year.
Separate investments have their own tax rules:
*Equity mutual funds generally follow equity-oriented fund taxation.
*Listed gold ETFs held for more than 12 months qualify for long-term capital gains treatment, generally at 12.5%, without the ₹1.25 lakh equity exemption.
*Gains from specified debt mutual funds acquired on or after April 1, 2023, are generally taxed at the investor's applicable income-tax slab rate, irrespective of the holding period.
A multi-asset fund that does not qualify for equity-oriented taxation may receive a different tax treatment.
Check the scheme's classification and current tax rules before investing. Tax can make a meaningful difference to your post-tax returns.
6/8
Separate investments give you greater control, while multi-asset funds offer a simpler way to manage diversification
A multi-asset fund gives you one scheme to monitor and one fund manager responsible for managing the asset mix.
But you cannot independently increase gold exposure or sell only the debt portion. You must work within the fund's investment strategy.
Separate investments give you the freedom to choose your equity fund, gold ETF and debt product independently. You can also adjust each allocation to match your financial goals.
However, this means tracking multiple investments, expense ratios, tax liabilities and portfolio weightages.
Convenience has value, but so does control. Your choice should reflect how actively you want to manage your money.
But you cannot independently increase gold exposure or sell only the debt portion. You must work within the fund's investment strategy.
Separate investments give you the freedom to choose your equity fund, gold ETF and debt product independently. You can also adjust each allocation to match your financial goals.
However, this means tracking multiple investments, expense ratios, tax liabilities and portfolio weightages.
Convenience has value, but so does control. Your choice should reflect how actively you want to manage your money.
7/8
Multi-asset funds and separate investments suit different investors: here is what to consider
Multi-asset funds may suit investors who:
*Want exposure to different asset classes through one investment.
*Prefer professional portfolio management.
*Do not have the time or discipline to rebalance regularly.
*Are comfortable with the fund manager's investment decisions.
Separate investments may suit investors who:
*Want complete control over their asset allocation.
*Have the knowledge to select equity, gold and debt products.
*Want to customise their portfolio around financial goals.
*Can monitor investments and rebalance them consistently.
For instance, ICICI Prudential Multi Asset Fund and HDFC Multi Asset Allocation Fund are examples of schemes in this category. They have different investment strategies, so compare their portfolios, costs and risk profiles rather than choosing by name alone.
Also compare the combined cost of your separate investments with the multi-asset fund's expense ratio. Consider direct and regular plan costs separately.
*Want exposure to different asset classes through one investment.
*Prefer professional portfolio management.
*Do not have the time or discipline to rebalance regularly.
*Are comfortable with the fund manager's investment decisions.
Separate investments may suit investors who:
*Want complete control over their asset allocation.
*Have the knowledge to select equity, gold and debt products.
*Want to customise their portfolio around financial goals.
*Can monitor investments and rebalance them consistently.
For instance, ICICI Prudential Multi Asset Fund and HDFC Multi Asset Allocation Fund are examples of schemes in this category. They have different investment strategies, so compare their portfolios, costs and risk profiles rather than choosing by name alone.
Also compare the combined cost of your separate investments with the multi-asset fund's expense ratio. Consider direct and regular plan costs separately.
8/8
The better choice is not the one with more assets, but the one you can manage consistently
Choose a multi-asset fund if you value convenience, professional allocation management and a single investment structure.
Choose separate investments if you want greater control over your equity, gold and debt exposure and are willing to manage rebalancing yourself.
Before investing, examine the asset allocation, fund strategy, expense ratio, tax classification and performance across different market conditions.
Do not compare returns without considering the underlying asset mix, investment period, costs and taxes.
Remember, diversification can spread risk, but it cannot eliminate losses or guarantee returns.
The goal is not to own more investments. It is to build an allocation that supports your financial goals and that you can stick with through different market cycles.
Sources: SEBI, AMFI, Income Tax Department, HDFC Mutual Fund, ICICI Prudential Mutual Fund and Value Research.
Note: The ₹10 lakh portfolio allocation is illustrative, not an actual fund portfolio or investment recommendation. Fund allocations and tax treatment are subject to change.
Disclaimer: This article is for informational purposes only and should not be treated as investment or tax advice.
Choose separate investments if you want greater control over your equity, gold and debt exposure and are willing to manage rebalancing yourself.
Before investing, examine the asset allocation, fund strategy, expense ratio, tax classification and performance across different market conditions.
Do not compare returns without considering the underlying asset mix, investment period, costs and taxes.
Remember, diversification can spread risk, but it cannot eliminate losses or guarantee returns.
The goal is not to own more investments. It is to build an allocation that supports your financial goals and that you can stick with through different market cycles.
Sources: SEBI, AMFI, Income Tax Department, HDFC Mutual Fund, ICICI Prudential Mutual Fund and Value Research.
Note: The ₹10 lakh portfolio allocation is illustrative, not an actual fund portfolio or investment recommendation. Fund allocations and tax treatment are subject to change.
Disclaimer: This article is for informational purposes only and should not be treated as investment or tax advice.
READ MORE:
Multi asset allocation fund |Multi asset mutual funds |Multi asset fund vs separate investments |Multi asset fund vs individual investments |Equity gold and debt investment |₹10 lakh investment strategy |Best way to diversify investment portfolio |Multi asset mutual fund taxation |Equity gold debt portfolio