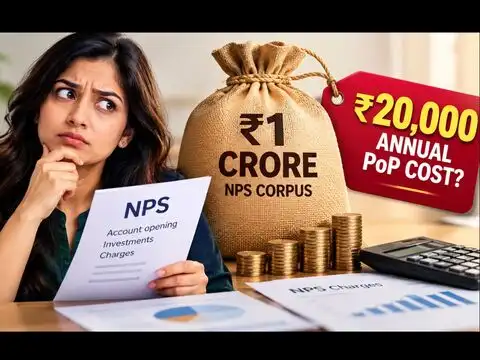
NPS charges: ₹1 crore corpus could mean ₹20,000 annual PoP cost; check this before opening an account
1/9
NPS charges: Your account-opening route can affect costs
When choosing the National Pension System (NPS), returns and tax benefits are not the only things to compare. The way you open and operate your account can also affect costs. From October 1, 2026, the standardised Point of Presence (PoP) structure makes the choice between direct e-NPS and PoP-based onboarding especially important for new subscribers.
2/9
What is the NPS PoP charge?
A Point of Presence, or PoP, is an intermediary that helps subscribers open and service an NPS account. From October 1, 2026, the annual PoP charge remains 0.20% of the NPS corpus, plus applicable taxes, for existing subscribers in the specified common NPS schemes, NPS Lite and NPS Vatsalya. New PoP accounts also have a one-time ₹200 onboarding charge, subject to applicable rules.
3/9
₹1-crore NPS corpus: 0.20% means ₹20,000 a year
The 0.20% PoP charge may look small, but its rupee impact rises as your retirement corpus grows. On a ₹5 lakh corpus, it works out to ₹1,000 a year. At ₹25 lakh, it becomes ₹5,000; at ₹50 lakh, ₹10,000; and at ₹1 crore, ₹20,000 a year. These figures are before applicable taxes and other NPS charges.
4/9
₹10,000 monthly NPS investment: Cost rises as corpus grows
Consider an investor contributing ₹10,000 every month and earning an illustrative 10% annual return. After 10 years, the estimated corpus is about ₹20.1 lakh, making the 0.20% PoP charge around ₹4,020. After 20 years, the corpus could reach ₹72.4 lakh, taking the annual charge to ₹14,480. After 30 years, a ₹2.1 crore corpus would mean about ₹42,000 annually.
5/9
Is 0.20% the total cost of investing in NPS?
No. The PoP charge is only one component of NPS costs. Subscribers may also incur pension fund management charges, record-keeping charges, NPS Trust and custodian charges, along with applicable taxes. Therefore, comparing NPS costs only on the basis of the 0.20% PoP fee can give an incomplete picture. Investors should check the entire applicable charge structure before choosing their onboarding route.
6/9
e-NPS vs PoP: Which route costs less?
For a new subscriber, the onboarding route matters. A subscriber who opens an account directly through e-NPS and continues making contributions through e-NPS or D-Remit does not pay a PoP charge. A PoP can offer assisted account-opening and servicing, but the convenience comes with the applicable PoP fee. Compare the service support against the potential long-term cost before deciding.
7/9
Already have NPS through PoP? D-Remit won't remove the fee
Simply switching your contribution method does not change how your NPS account was originally opened. If your PRAN was opened through a PoP, making later contributions through e-NPS or D-Remit does not automatically eliminate the applicable PoP charge. Existing subscribers can explore the change-of-PoP facility, but whether this reduces the charge depends on the applicable PFRDA framework and PoP arrangement.
8/9
Does D-Remit make NPS cheaper?
D-Remit is a direct bank-transfer facility that makes NPS contributions easier, but it does not automatically make a PoP-based account free of PoP charges. The key distinction is how the PRAN was opened. Direct e-NPS onboarding + e-NPS/D-Remit contributions means no PoP charge, while PoP onboarding + e-NPS/D-Remit contributions continues to attract the applicable PoP charge.
9/9
How are NPS charges deducted from your account?
The annual PoP fee does not necessarily appear as a separate debit from your bank account. According to the source, it is reflected through the value of NPS units or NAV. The one-time onboarding fee is recovered by cancelling units. GST and other applicable taxes are additional. Existing subscribers should check their PRAN, applicable PoP and the complete NPS charge schedule before assuming online contributions reduce costs.