Investment mistakes to avoid: 8 silent risks that decide whether your money actually grows
1/9
The risks you never see are the ones that hurt most
India's investors are focused on long-term wealth creation, but the bigger challenge is often understanding the hidden risks that stop investors from actually capturing the returns markets offer. DSP's September edition of Netra – Early Signals Through Charts looks beyond headline performance to examine what really shapes outcomes: investor behaviour, timing, affordability, concentration, diversification, and small recurring frictions.
Most of what damages real investor returns hides in plain sight for years before it shows up. Here are seven of those risks, made visible.
Most of what damages real investor returns hides in plain sight for years before it shows up. Here are seven of those risks, made visible.
2/9
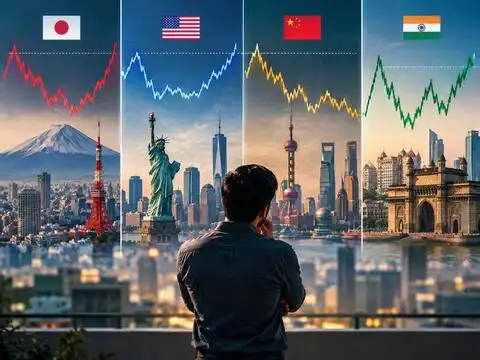
Risk 1: You don't get to choose your 40-year market
Japan's Nikkei took until 2025 to reclaim its December 1989 peak, a 35-year round trip with an 80% drawdown along the way. The S&P 500 went flat for 13 years after its 2000 high. China's CSI 300 is still below its 2007 level. India's Sensex round-tripped for over a decade after 1992, with two separate collapses in between.
The era you happen to invest in decides more than any single choice you make inside it. Diversification and the price you pay are the only two things you actually control.
The era you happen to invest in decides more than any single choice you make inside it. Diversification and the price you pay are the only two things you actually control.
3/9
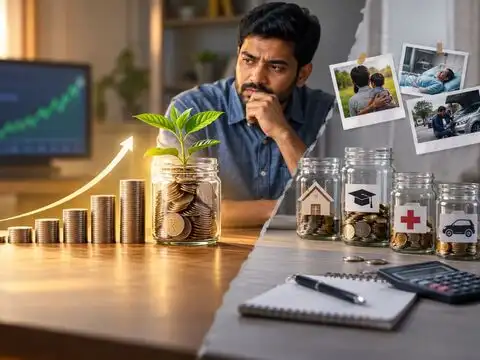
Risk 2: SIPs look perfect on paper. Life isn't a spreadsheet.
A flat ₹10,000 monthly SIP since 2006 turned ₹24 lakh invested into roughly ₹87 lakh. But most people's ₹10,000 wasn't ₹10,000 twenty years ago, it was a much bigger share of what they earned back then. Adjust the SIP for what income actually allowed, and the invested amount falls to about ₹12 lakh, and the corpus to under ₹32 lakh.
Add in the real-world habit of pausing a SIP at the wrong moment, or withdrawing early for an urgent need, and the gap between the spreadsheet and real life grows wider still.
Add in the real-world habit of pausing a SIP at the wrong moment, or withdrawing early for an urgent need, and the gap between the spreadsheet and real life grows wider still.
Amazon Top Deals
POWERED BY
4/9
Risk 3: The market's average return isn't your return
An index's headline average smooths over a bumpy ride that most investors never actually experience. Your outcome depends on when your money enters and exits, not just where the index ends up years later.
Rupee-cost averaging helps — buying more units when prices are low, fewer when they're high — but even then, the "average investor" and the "average market" are two very different numbers.
Rupee-cost averaging helps — buying more units when prices are low, fewer when they're high — but even then, the "average investor" and the "average market" are two very different numbers.
5/9
Risk 4: Same fund. same period. Wildly different experience.
Between 1998 and 2003, the Kinetics Internet Fund reported a return of +8.3% a year. The investors actually in the fund, weighted by when their money arrived, lost 11.9% a year. Money flooded in right after the big early gains — just before the crash.
Even over the long run through 2026, with the fund up 10.4% annually, investors captured only 0.4%. The fund made money. Most of the people in it didn't.
Even over the long run through 2026, with the fund up 10.4% annually, investors captured only 0.4%. The fund made money. Most of the people in it didn't.
6/9
Risk 5: Money always arrives late to the party
Small cap funds, momentum funds, infrastructure funds, technology funds — across every category, the same pattern shows up. Flows surge after a category has already rallied hard, and dry up right as returns start cooling.
On average, investors end up buying after the gains and selling after the losses, simply by following performance instead of a plan.
On average, investors end up buying after the gains and selling after the losses, simply by following performance instead of a plan.
7/9
Risk 6: Your return gets decided on about 10 days
Across 11,025 trading days of the Sensex since 1979, staying invested every single day turned ₹1 into 607 times as much. Miss just the ten best days and that multiple falls to 213 times. Miss the ten worst days instead, and it climbs to 1,733 times.
A handful of days scattered across decades decide the whole outcome — which is exactly why staying invested tends to beat trying to time it.
A handful of days scattered across decades decide the whole outcome — which is exactly why staying invested tends to beat trying to time it.
8/9
Risk 7: Almost all the wealth comes from almost none of the stocks
Of 63,785 global companies tracked from 1990 to 2020, just the top 2.39% created nearly all the net wealth created in that period. The rest, together, barely moved the needle.
It's the same story with the names investors fell in love with: Enron, Peloton, Carvana, Nikola and many other once-popular stocks later fell 60–100% from their peaks. Tomorrow's big winners are only obvious in hindsight — a good story is not a strategy.
It's the same story with the names investors fell in love with: Enron, Peloton, Carvana, Nikola and many other once-popular stocks later fell 60–100% from their peaks. Tomorrow's big winners are only obvious in hindsight — a good story is not a strategy.
9/9
What you can't see is what can hurt you most
A flat decade you didn't choose. A SIP you couldn't really afford to keep. A fund you joined too late. Ten days you weren't around for. Every risk here stayed silent until it wasn't.
None of it is solved by prediction. It's solved by staying diversified, keeping costs and activity low, and trusting discipline over luck.
Source: Adapted from "Netra — Early Signals Through Charts," DSP Mutual Fund, September 2026. Mutual fund investments are subject to market risk. Read all scheme documents carefully.