₹250 to start a child’s retirement fund: Does this govt-backed scheme give higher returns than PPF, SSY?
1/7
Retirement fund for your child
Did you know that you can create a sizeable retirement fund for your children (both daughter and son), with an amount as low as Rs 250? One of the best features of this government-backed scheme is that it offers the benefit of compounding when investing for a long time.
2/7
Government-backed scheme to create a retirement fund for children
Launched two years ago, NPS Vatsalya is a long-term financial security scheme for minors. Under this scheme, a parent or legal guardian opens and operates an account in the name of their minor child.
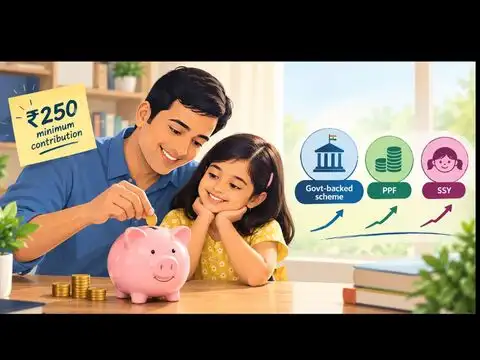
Parents can start with a minimum annual deposit of Rs 250, with no maximum limit. When the child turns 18, the NPS Vatsalya account will convert into a regular NPS pension account.
Parents can start with a minimum annual deposit of Rs 250, with no maximum limit. When the child turns 18, the NPS Vatsalya account will convert into a regular NPS pension account.
3/7
NPS Vatsalya returns: Higher than PPF, SSY?
While Sukanya Samriddhi Yojana (SSY) currently offers 8.2%, Public Provident Fund (PPF) offers 7.1%. NPS Vatsalya, on the other hand, is a market-linked scheme and so has the potential to deliver higher returns than SSY and PPF.
Contributions are invested by the selected Pension Fund, and may allocate up to 100% to Equity.
Alternatively, it may invest with limits of 75% for equity, 20% for government securities, 30% for debt instruments and 10% for money market instruments.
Contributions are invested by the selected Pension Fund, and may allocate up to 100% to Equity.
Alternatively, it may invest with limits of 75% for equity, 20% for government securities, 30% for debt instruments and 10% for money market instruments.
Amazon Top Deals
POWERED BY
4/7
Can I make partial withdrawals in NPS Vatsalya?
Yes, the scheme lets subscribers make partial withdrawals after completing a lock-in of 3 years from account opening. A maximum of up to 25% of the minor subscriber's own contributions, excluding returns, can be withdrawn.
Permitted purposes: Education of the minor subscriber, treatment of specified illnesses, and disability of more than 75% of the minor subscriber.
(NOTE: Only 2 partial withdrawals can be made before the minor turns 18)
Permitted purposes: Education of the minor subscriber, treatment of specified illnesses, and disability of more than 75% of the minor subscriber.
(NOTE: Only 2 partial withdrawals can be made before the minor turns 18)
5/7
What happens to NPS Vatsalya when the child turns 18?
On attaining 18 years of age: Subscriber can continue in NPS Vatsalya up to 21 years
Shift to NPS: They can shift the entire accumulated corpus to NPS.
Exit NPS Vatsalya: If corpus is below Rs 8 lakh, the entire corpus can be withdrawn in lump sum. If corpus is Rs 8 lakh or more, up to 80% can be withdrawn as lump sum and 20% is to be utilised for the purchase of annuity.
Shift to NPS: They can shift the entire accumulated corpus to NPS.
Exit NPS Vatsalya: If corpus is below Rs 8 lakh, the entire corpus can be withdrawn in lump sum. If corpus is Rs 8 lakh or more, up to 80% can be withdrawn as lump sum and 20% is to be utilised for the purchase of annuity.
6/7
NPS Vatsalya tax benefits: Old regime vs new regime
Contributions made to the scheme qualify for up to Rs 50,000 tax deduction under the old regime. However, this deduction is not available in the new tax regime.
In case of partial withdrawals, up to 25% of own contribution is exempt in both tax regimes.
On exit/closure of NPS Vatsalya account, lump-sum withdrawal up to 60% of the corpus is tax-exempt in both regimes.
Amount used for the purchase of an annuity is exempt at purchase in both regimes.
In case of partial withdrawals, up to 25% of own contribution is exempt in both tax regimes.
On exit/closure of NPS Vatsalya account, lump-sum withdrawal up to 60% of the corpus is tax-exempt in both regimes.
Amount used for the purchase of an annuity is exempt at purchase in both regimes.
7/7
What happens if NPS Vatsalya subscriber dies?
In such a case, the entire pension wealth is payable to the guardian, nominee(s) or legal heir(s). Moreover, the receiver would also have the option to transfer the money to an NPS account.