Delivery can cost ₹1.5 lakh to ₹3 lakh: What maternity insurance in India covers and what it doesn’t
1/9
Pregnant? Is your insurance ready?
The good news arrives first. The insurance question usually comes a week later, often at 1 a.m. on a search engine. For most couples who haven’t planned ahead, the honest answer is not a comfortable one. A policy bought after you conceive will not pay for the delivery, because maternity cover works on a waiting period. The best time to think about it is one to three years before you plan a baby. Read on to see how to line up cover in time.
2/9
Why your policy may not pay for delivery
Maternity is not covered by default. IRDAI’s standard list of exclusions includes childbirth expenses, even complicated deliveries and C-sections, unless your policy specifically adds maternity cover. Ectopic pregnancy is the exception and is usually treated as a regular hospitalisation. Check the exclusions section of your policy and confirm the current wording with IRDAI.
3/9
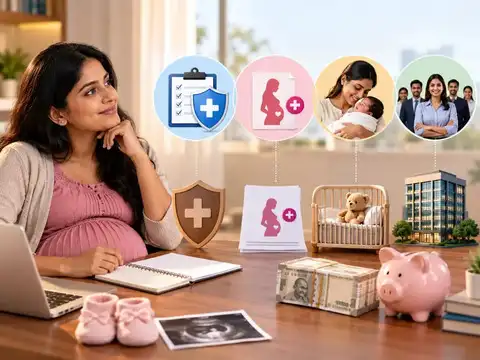
4 ways to get maternity cover
Built-in benefit: Some comprehensive plans include it, but watch for low limits and long waiting periods
Add-on or rider: An extra premium on your regular plan, with its own sub-limit and waiting period
Maternity-focused plans: Built around pregnancy and newborn benefits, but premiums can be high compared with the payout
Employer group cover: Often includes maternity, sometimes from day one, but it ends when the job ends
4/9
What a delivery really costs
Delivery in a private hospital in a Tier-1 city has been reported to cost roughly ₹1.5 lakh to ₹3 lakh, including prenatal tests. This is an approximate range, and costs vary by city, hospital and complications. An emergency C-section or a NICU stay can push the bill higher. Maternity cover is expensive because insurers can see the claim coming, so they add waiting periods, low sub-limits and caps on the number of deliveries.
5/9
The waiting period is the catch
Maternity waiting periods commonly run from 9 months to 4 years, and 2 to 3 years is typical for add-ons. The clock starts when your maternity cover begins, not when you first bought any health policy. Many plans also need both partners on the same policy. Read the wording closely, because some plans tie eligibility to the date of delivery and others to the date pregnancy is diagnosed. If you want a baby in three years, buy a three-year-wait plan today.
6/9
What is covered, and what is not
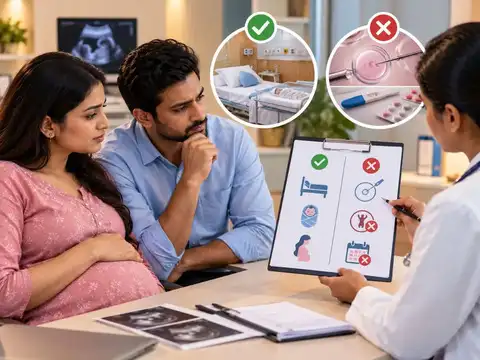
Most plans cover normal and C-section delivery, but only within a sub-limit, and the normal delivery cap is often lower. Prenatal and postnatal costs are covered only sometimes, usually when linked to the delivery hospitalisation. Newborn cover, NICU stays and vaccinations vary widely. Common exclusions include a pregnancy that already exists when you buy, infertility treatment such as IVF and IUI, voluntary termination that is not medically necessary, and deliveries beyond the plan’s cap, which is often two.
7/9
Is it worth it? Run the numbers
Here is a hypothetical example. Aditi and Rohit, both 29, pay ₹15,000 a year for a maternity add-on with a 3-year wait. In year four they have a C-section costing ₹1.8 lakh. The add-on pays its ₹75,000 cap, so they still fund ₹1.05 lakh themselves. Over three years they paid ₹45,000 in extra premiums, so the add-on gained them ₹30,000. If they had invested the same money at an assumed 7% a year, they would have about ₹51,600. The add-on still comes out ahead, but only by a modest amount, so calculate before you buy.
8/9
Newborn cover is the real prize
Complications can cost more than the delivery itself. In the same example, 8 days in NICU at about ₹25,000 a day comes to ₹2 lakh. If newborn cover starts from day one, the insurer largely pays. If it starts only from day 91, the family pays the full amount. Employer cover can help too. In one example, a group policy with ₹80,000 maternity cover and no waiting period paid most of a ₹1.1 lakh normal delivery. But changing jobs mid-pregnancy could mean losing that cover, so plan job moves around your due date.
9/9
Already pregnant? Do this now
You still have options. Check your employer’s maternity and newborn benefits and how to claim. Build a delivery fund from your hospital’s package estimate plus a buffer for complications. Ask your insurer how and when a newborn can be added to your policy. Check whether government maternity schemes apply to you on official websites. If you want another child, start the waiting-period clock now. Before buying any plan, compare the waiting period, normal and C-section sub-limits, newborn and NICU rules, the number of deliveries covered, and whether both partners must be on the policy.
All case figures are hypothetical and for illustration. This is general information, not personalised insurance or financial advice. Check your policy wording and current IRDAI rules before you decide.
All case figures are hypothetical and for illustration. This is general information, not personalised insurance or financial advice. Check your policy wording and current IRDAI rules before you decide.