Is your loan waived or just written off? The difference can wreck your credit score
1/7
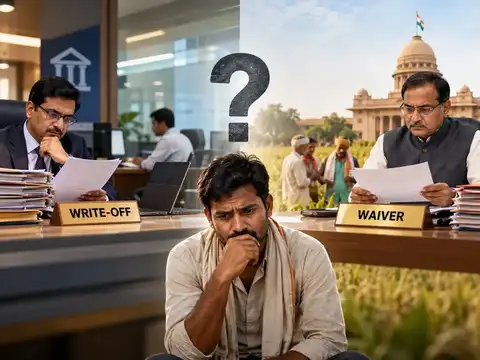
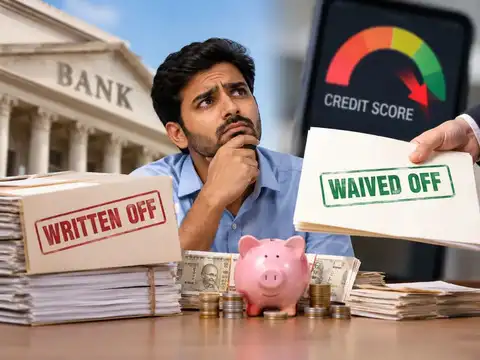
Written off ≠ Waived off. Know the difference
Banks use both terms, and most borrowers mix them up. One clears the bank's books. The other clears your debt. Swipe to see why that gap matters for your money and your credit score.
2/7
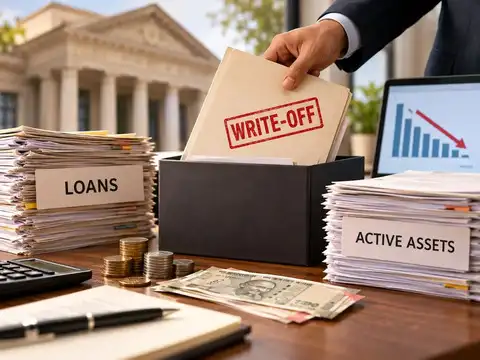
A write-off is just bookkeeping
When a loan goes bad and recovery looks unlikely, the bank moves it off its active assets. This cleans up the balance sheet and lowers the bank's reported bad loans (NPAs). It is an internal accounting step, and the bank decides it alone.
3/7
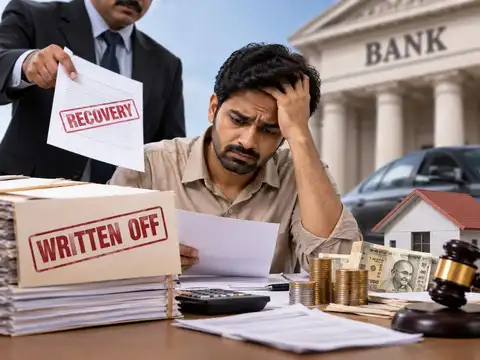
Written off? You still owe it
A write-off does not cancel your loan. You are still legally required to repay 100% of the amount. The bank can still send recovery agents, take legal action, or seize collateral. The bank has only stopped counting the loan as an asset.
Amazon Top Deals
POWERED BY
4/7
A waiver wipes the slate clean
A waiver is real forgiveness. The loan account is closed, your repayment duty ends, and the lender cannot chase you for the waived amount. If you pledged collateral, the lender has to return it.
5/7
Who makes the call?
Write-offs are the lender's own decision, made after recovery efforts fail. Waivers usually need a government scheme or a lender policy behind them, such as relief for farmers after a failed harvest. Borrowers must meet specific criteria, and the reason for non-payment is checked first.
6/7
Your credit score feels it
A write-off leaves a severe negative mark on your credit report, and your score can drop heavily. A waiver has a milder, less predictable effect, but it can still affect your credit history. Neither one is a free pass.
7/7
The takeaway
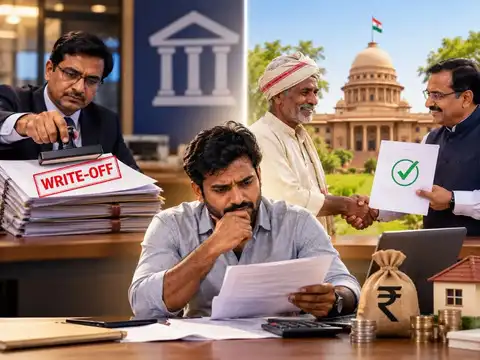
Write-off: the bank closes the books, but you still owe the money. Waiver: the debt is gone for good. If you are struggling to repay, talk to your lender early, before the loan turns bad. Waivers are not something you can simply apply for, because they depend on government or lender schemes.