Drowning in credit card bills? Know RBI rights and your best options to escape debt trap
1/10
Escape credit card debt in India: 6 ways to get out for good
Credit card debt can feel impossible when interest runs at 36% to 40% a year or more. You can still beat it with a clear plan. This guide covers how to stop new charges, pick a repayment method, cut your interest cost and use your rights if the bank pressures you.
2/10
Step One: Stop the bleeding
Before you pay anything off, stop adding to the pile. Put your cards away or freeze them in your bank’s mobile app so you cannot spend by habit. Then write down every card, its total balance, its minimum due date and its yearly interest rate. Once you see the whole picture on one page, you can choose the right way out.
3/10
Why card debt grows so fast
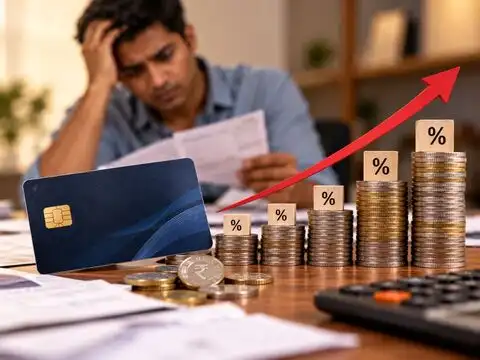
Credit card interest is far higher than almost any other loan, often 36% to 40% a year or more. Paying only the minimum keeps you in debt for years, because most of each payment goes to interest. Missing payments adds late fees, can end your interest-free period, can lower your credit limit and drags down your credit score. Every month you wait costs more.
4/10
Pay more than the minimum
If you can afford it, always pay more than the minimum due. Interest is charged on the balance, so every extra rupee you pay cuts the interest you owe from the next day on. Even a small extra amount shortens the time it takes to clear the debt. Paying the full balance every month is best, because it avoids interest completely.
5/10
Avalanche: Beat the highest interest first
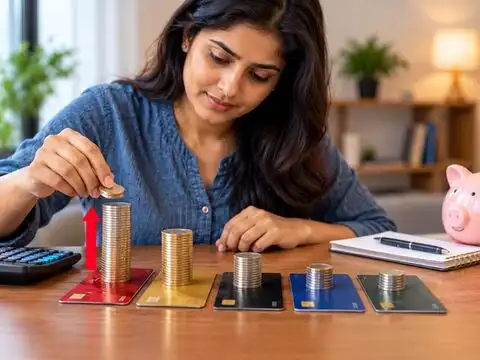
Pay the minimum on every card, then put all your spare money on the card with the highest interest rate. When it is cleared, move to the card with the next highest rate. This method usually saves the most money, because the costliest debt disappears first. It works best when you have steady monthly cash flow and can pay more than the minimum.
6/10
Snowball: Win small to stay motivated
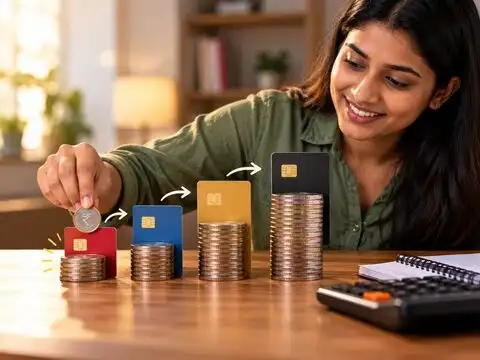
Pay the minimum on every card, then put your spare money on the smallest balance. When it is gone, roll that payment onto the next smallest, and so on. You may pay a little more interest than with the avalanche method, but quick wins keep many people going. Pick the method you will actually stick with.
7/10
Swap 40% interest for a 12% to 16% loan
If your credit score is still decent, a personal loan at around 12% to 16% can pay off all your card balances at once. You are left with one fixed monthly EMI at a much lower rate. A balance transfer to a card with a lower rate works the same way, and is open to people who have paid their minimum dues on time. Compare processing fees before you sign.
8/10
Can’t pay? Ask your bank for help
Call your bank and ask to convert your outstanding bill into fixed, lower-interest EMIs. This gives you a longer window to pay without defaulting. If you are 90 or more days behind and face genuine hardship, you can ask for a one-time settlement, where you pay a reduced lump sum, often 40% to 70% of what you owe. A settlement is usually recorded on your credit report and can make future loans harder to get, so treat it as a last resort.
9/10
Know your RBI rights
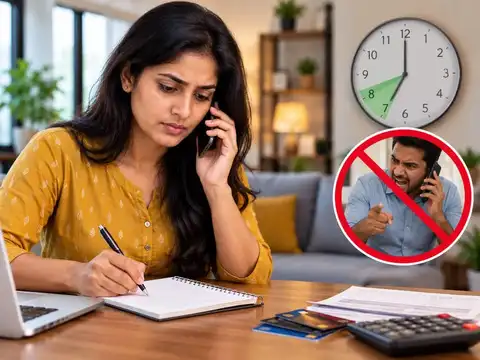
Recovery agents must follow Reserve Bank of India guidelines. They can contact you only between 8:00 AM and 7:00 PM. They must be polite and must never threaten or harass you. If an agent breaks these rules, note the date and time, then complain to the bank in writing.
10/10
Stay out of debt for good
Set up auto-pay so you never miss a due date, and keep enough money in your account to cover it. Build a realistic budget so spending does not outrun your savings. Switch to cash for everyday spending, which makes you feel every rupee. Aim to clear your card debt within about 36 months, and pay your full balance every month once you are free.