Closed loan still showing up as active on your credit report? Here is how to fix it in 3 steps
1/7
Closed loan still showing as active on your credit report? Here is the 3-step fix
You paid off your loan, but your credit report still lists it as active. This is a common problem, and it can be fixed. The process comes down to three steps: gather your closure proof, ask your lender to update the credit bureau, and raise a dispute if the report still does not change. Swipe through to see exactly what to do.
2/7
Why is your paid-off loan still active? Delays and data mismatches are the usual culprits
A loan usually shows as active after closure because of delayed lender updates, credit bureau processing time or minor data mismatches. In most cases it is not a sign that you did anything wrong. An incorrectly active loan can slightly reduce your credit score until the record is corrected, so it is worth fixing quickly rather than waiting and hoping.
3/7
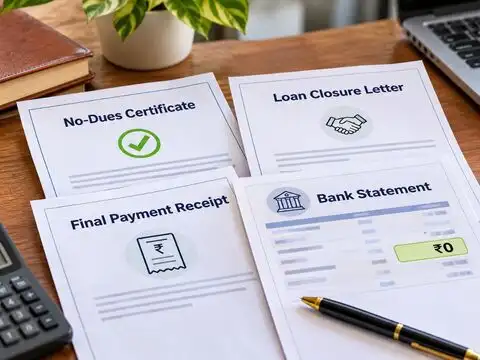
Step 1: Collect these 4 documents to prove your loan is fully paid
Before you contact anyone, gather your proof of closure:
*A No-Dues Certificate (NDC) or No Objection Certificate (NOC)
*Your loan closure letter
*The final payment receipt
*Bank statement entries showing a zero balance or your final EMI deduction
Keep digital and printed copies. These papers are your evidence if a dispute is needed later.
*A No-Dues Certificate (NDC) or No Objection Certificate (NOC)
*Your loan closure letter
*The final payment receipt
*Bank statement entries showing a zero balance or your final EMI deduction
Keep digital and printed copies. These papers are your evidence if a dispute is needed later.
4/7
Closed vs settled: Check your loan status before you make a single call
Check whether your loan was marked “Closed”, meaning fully repaid, or “Settled”, meaning paid at a reduced amount. A settled status behaves differently on your credit report, so the steps for a fully repaid loan may not fix it. Confirm which status your lender has recorded on your closure letter before you go further.
5/7
Step 2: Ask your lender to update the credit bureaus and confirm in writing
Contact your bank or NBFC through customer care or your local branch. Give them your Loan Account Number (LAN) and copies of your closure documents. Ask them to confirm in writing that they have reported the updated status to bureaus such as CIBIL, Experian, Equifax or CRIF High Mark. Lenders typically take 30 to 45 days to refresh and submit this data, so allow that time before escalating.
6/7
Step 3: Still active after weeks? File a dispute directly with the credit bureau
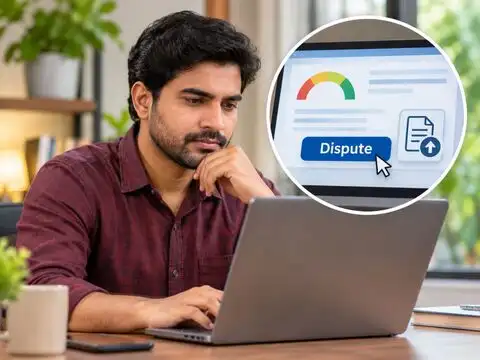
If your lender confirms it reported the closure but your report still shows the loan as active after several weeks, file a dispute on the bureau’s online portal, such as the CIBIL Dispute Resolution Portal. Select the incorrect account entry and upload your NOC, closure letter or payment receipts as proof. The bureau will re-verify the details with your lender, and this usually takes up to 30 days.
7/7
How long does it take, and how do you stop it happening again?
Loan closure typically takes 30 to 45 days to reflect once lenders and bureaus update their records, and a dispute can add up to 30 more days. To prevent the problem, check your credit report regularly, keep your closure proof safe and make sure your lender confirms that it has sent the data to the bureaus. A few minutes of checking can protect your credit score.