Microsoft to triple data centre capacity: What it means for investors
1/7
Microsoft’s massive AI infrastructure bet
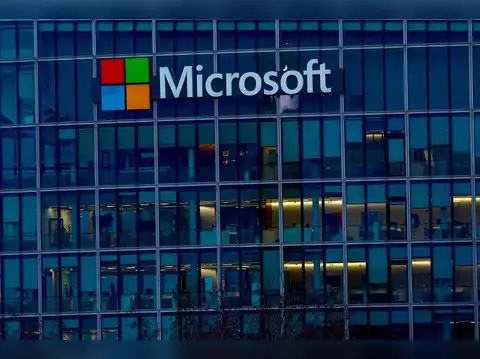
Microsoft is planning to expand its global data centre capacity to more than 38 gigawatts by 2032, up from around 12 gigawatts currently. The expansion aims to meet growing demand for artificial intelligence and cloud computing. (Source: GuruFocus, Simply Wall St)
2/7
AI demand is driving the infrastructure push
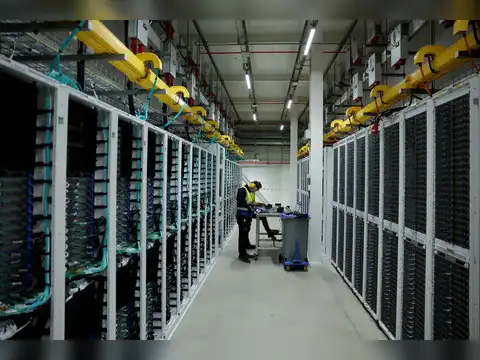
Microsoft has faced computing-capacity constraints as demand for AI and cloud services has accelerated. The new capacity is expected to give Azure greater ability to handle AI workloads while strengthening Microsoft's position in the highly competitive cloud market.
3/7
AI workloads at the centre of the expansion
Only a portion of Microsoft's existing data centre footprint is dedicated to AI-specific chips. The planned expansion is expected to substantially increase AI-related computing capacity, reflecting the company's expectation of sustained demand for AI training and inference.
Amazon Top Deals
POWERED BY
4/7
Will heavy AI spending translate into returns?
The infrastructure build-out strengthens Microsoft's ability to capture AI and cloud demand, but it also creates a major execution challenge. Simply Wall St notes that the key question for investors is whether heavy AI capital spending will translate into durable usage across Azure, Copilot and Microsoft's wider software ecosystem.
5/7
$678 billion backlog in focus
Microsoft's investment narrative is also supported by a reported $678 billion backlog, which could provide a significant pool of future revenue if converted into high-quality sales. Simply Wall St says the ability to turn this backlog into realised revenue remains an important part of the investment case.
6/7
GuruFocus sees valuation support
Microsoft was priced at $495.63, compared with a GF Value of $584.19, implying the stock was about 15.2% undervalued based on that methodology. Its GF Score stood at 99/100, with perfect scores for profitability, growth and valuation. The stock's trailing P/E of 27.6 times was also below its five-year median of 33.44 times, according to GuruFocus.
7/7
The key risk for Microsoft investors
The biggest concern is that Microsoft's AI infrastructure spending could run ahead of actual demand, putting pressure on free cash flow and margins. Power availability, capacity bottlenecks and execution also remain important risks as the company scales its data centre network.