Stocks to buy: Macquarie initiates Outperform rating on these 4 capital market stocks. Do you own any?
1/5
Bullish on Markets
Macquarie has issued a bullish call on India’s capital market industry and sees a powerful multiyear growth backdrop for market infrastructure firms as capital shifts into financial assets. The international brokerage in its report said Indians save $500 billion annually in financial assets and almost 50% of that is in cash and deposits. It added that this cash pool is ready for market-linked products which will drive a 16% CAGR in India’s combined investment and wealth and exchanges revenue pool over FY26-30. It expects brokers and exchanges to benefit from a larger investor base, rising engagement and broader monetisation across investment products. Here are the capital market stocks it initiated coverage with ‘Outperform’ rating, apart from Angel One on which it has a ‘Neutral’ rating.
2/5
Groww (Outperform; target price: Rs 260)
Macquarie gave Groww the tag of a ‘Disruptor’ as it named the stock its top pick in the capital market industry. It noted that Groww is India's largest digital-first broker and share gainer in a 17-18% TAM CAGR market, driving 25% FY26-30 revenue growth and EBITDA margins toward 70%. CAS is a near-term drag, while wealth, AMC and new products are unpriced, the international brokerage said. It has an ‘Outperform’ rating on the stock with a target price of Rs 260 apiece.
Also read | $500 billion flywheel! Macquarie lists 3 drivers for strong growth in capital market stocks, lists top picks
Also read | $500 billion flywheel! Macquarie lists 3 drivers for strong growth in capital market stocks, lists top picks
3/5
MCX (Outperform; target price: Rs 3,820)
Macquarie has an ‘Outperform’ rating on the shares of Multi Commodity Exchange of India (MCX) with a target price of Rs 3,820 apiece, noting that the market still underprices platform optionality and cash-return potential. MCX is India's near-monopoly commodity exchange, under-penetrated on investors, products and volumes, with a 19% FY26-30 revenue CAGR from broadening participation, it said, calling the commodity exchange the ‘Phoenix’.
Amazon Top Deals
POWERED BY
4/5
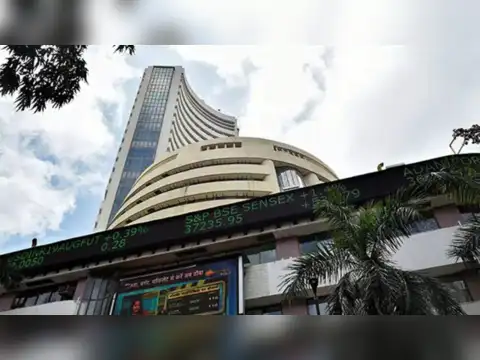
BSE (Outperform; target price: Rs 4,000)
Macquarie gave BSE the tag of a ‘Challenger’ as it initiated coverage on the stock with an ‘Outperform’ rating with a target price of Rs 4,000 apiece. The international brokerage noted that the stock exchange is a share gainer in a 12% TAM CAGR market, which can drive 16% FY26-30 revenue growth and margins toward 70%. CAS however is a near-term drag.
5/5
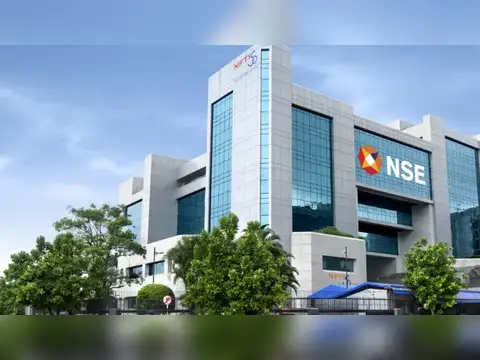
NSE (Outperform; target price: Rs 1,965)
Macquarie has an ‘Outperform’ rating on the shares of National Stock Exchange (NSE) with a target price of Rs 1,965 apiece, expecting the newly-listed company to see revenue grow 12% vs a 12-14% TAM CAGR over FY26-30. Like its peer BSE, CAS is a near-term drag for NSE too. The international brokerage called the stock exchange the ‘Dominator’.
Also read | NSE shares gain on debut day: How much Radhakishan Damani, Raamdeo Agrawal & other ace investors’ stakes are now worthDisclaimer: This article has been written by Debaroti Adhikary, who is not a SEBI-registered Research Analyst or an Investment Adviser. Debaroti Adhikary and his/her ‘relative(s)’ (as defined under Section 2(77) of the Companies Act, 2013) do not hold any financial interest in the companies mentioned in this article as of the date of publication. The views/recommendations mentioned in this article, wherever applicable, are those of the respective SEBI-registered Research Analyst/brokerage and have been reproduced/reported with due attribution. They should not be construed as the views or recommendations of The Economic Times Digital or the journalist. Readers are advised to consider the original research report and make their investment decisions based on their own assessment. Brokerage disclaimers here.
Also read | NSE shares gain on debut day: How much Radhakishan Damani, Raamdeo Agrawal & other ace investors’ stakes are now worthDisclaimer: This article has been written by Debaroti Adhikary, who is not a SEBI-registered Research Analyst or an Investment Adviser. Debaroti Adhikary and his/her ‘relative(s)’ (as defined under Section 2(77) of the Companies Act, 2013) do not hold any financial interest in the companies mentioned in this article as of the date of publication. The views/recommendations mentioned in this article, wherever applicable, are those of the respective SEBI-registered Research Analyst/brokerage and have been reproduced/reported with due attribution. They should not be construed as the views or recommendations of The Economic Times Digital or the journalist. Readers are advised to consider the original research report and make their investment decisions based on their own assessment. Brokerage disclaimers here.